
Premarket Price Action
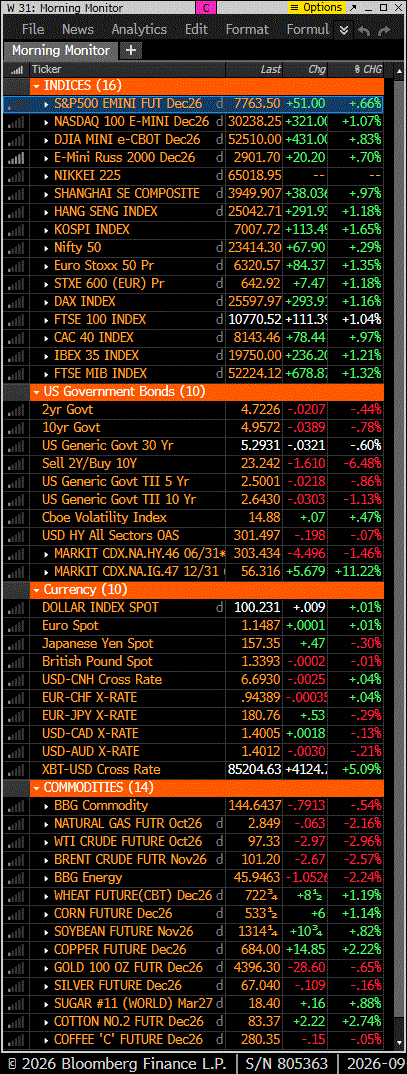
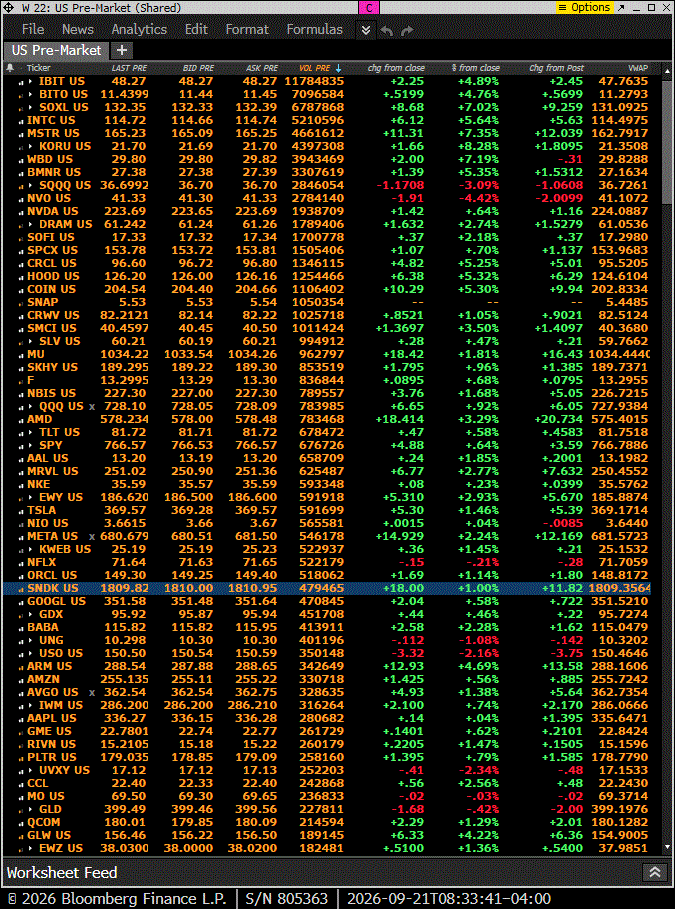
- US equity futures: S&P +0.65%, Nasdaq +1%, Russell 2000 +0.75%.
- Treasuries: Rates down 2–3bp across the curve, reversing some of Friday’s pressure.
- Dollar: DXY +0.1%.
- Crypto: Bitcoin futures +5.0%.
- Commodities: Gold −0.6%; silver is flat; WTI crude −2.5%, Natural gas: -2.2%
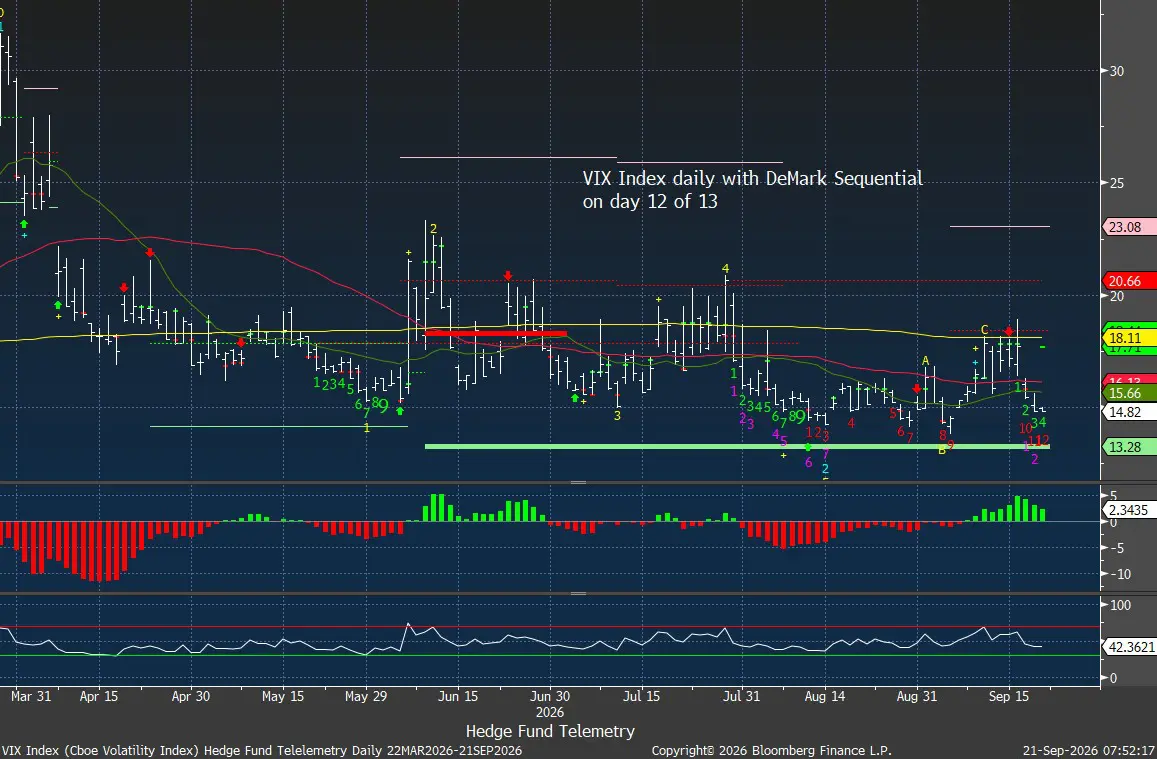
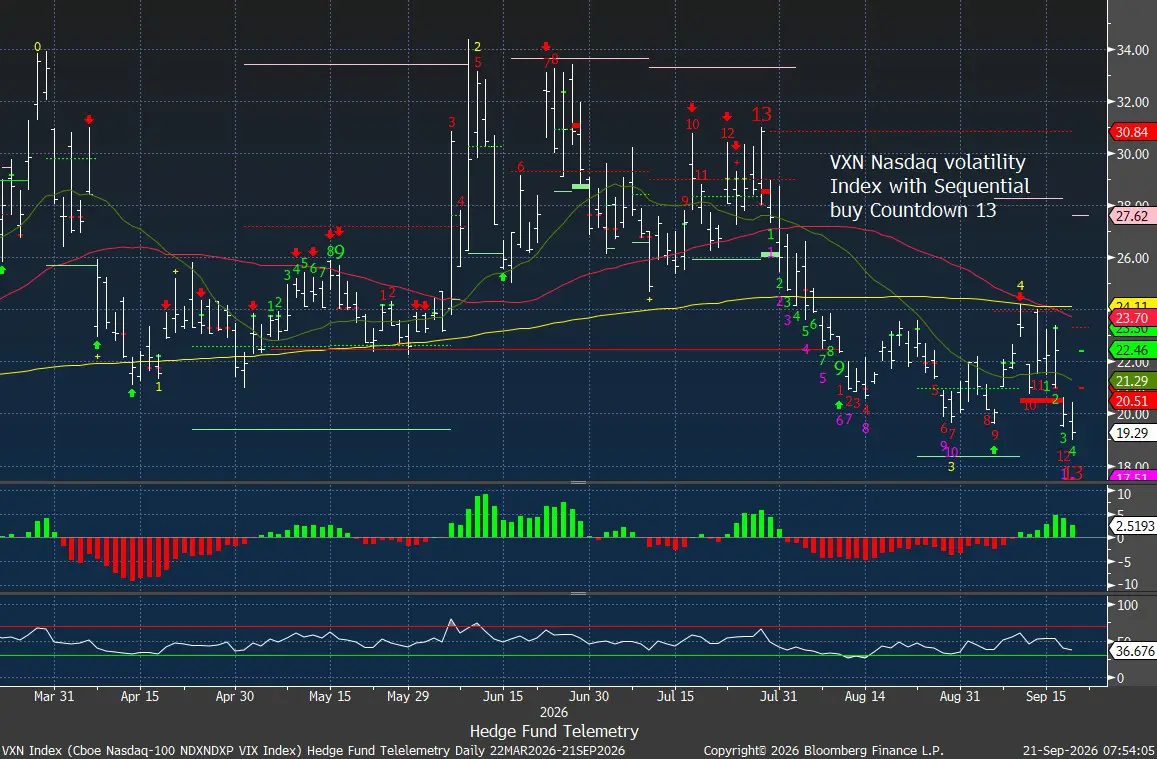
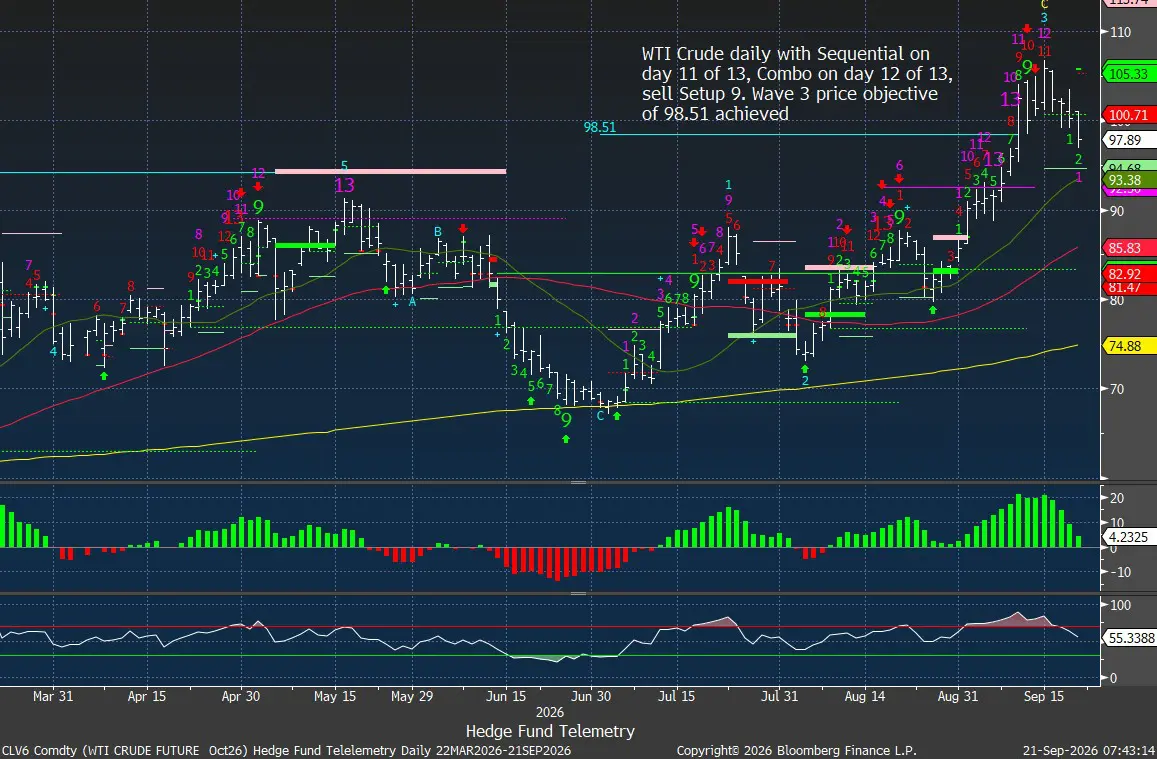
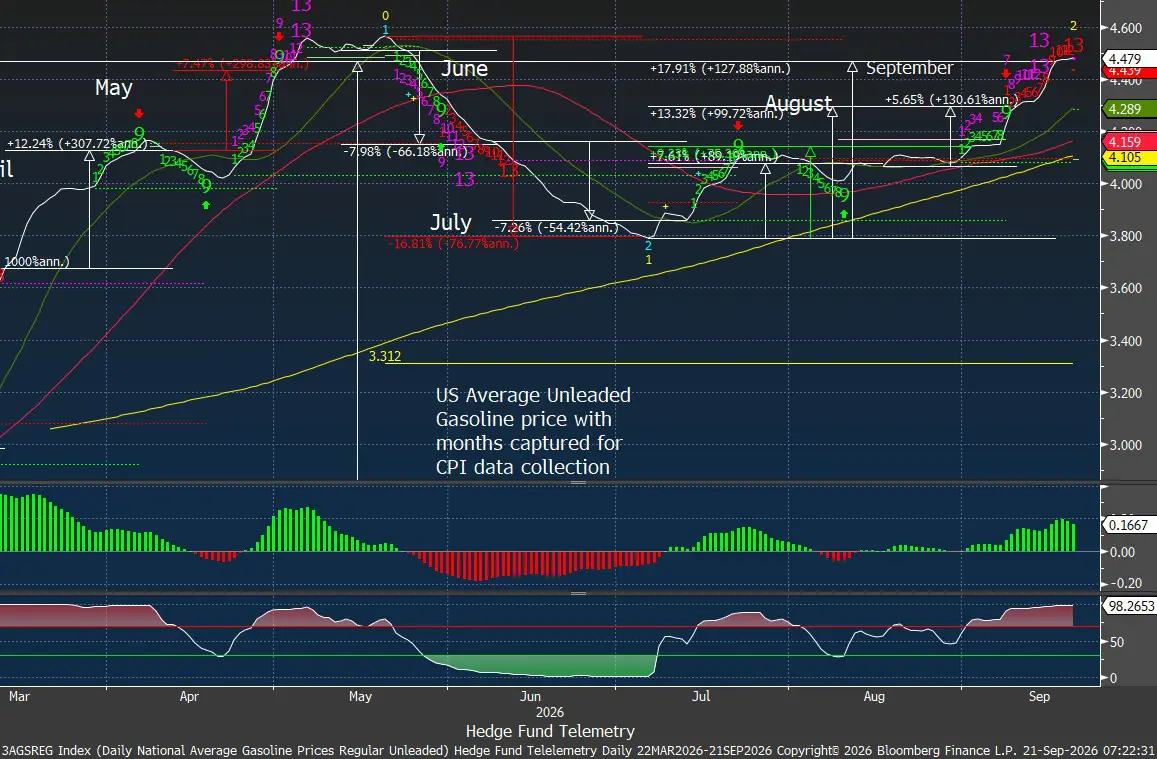
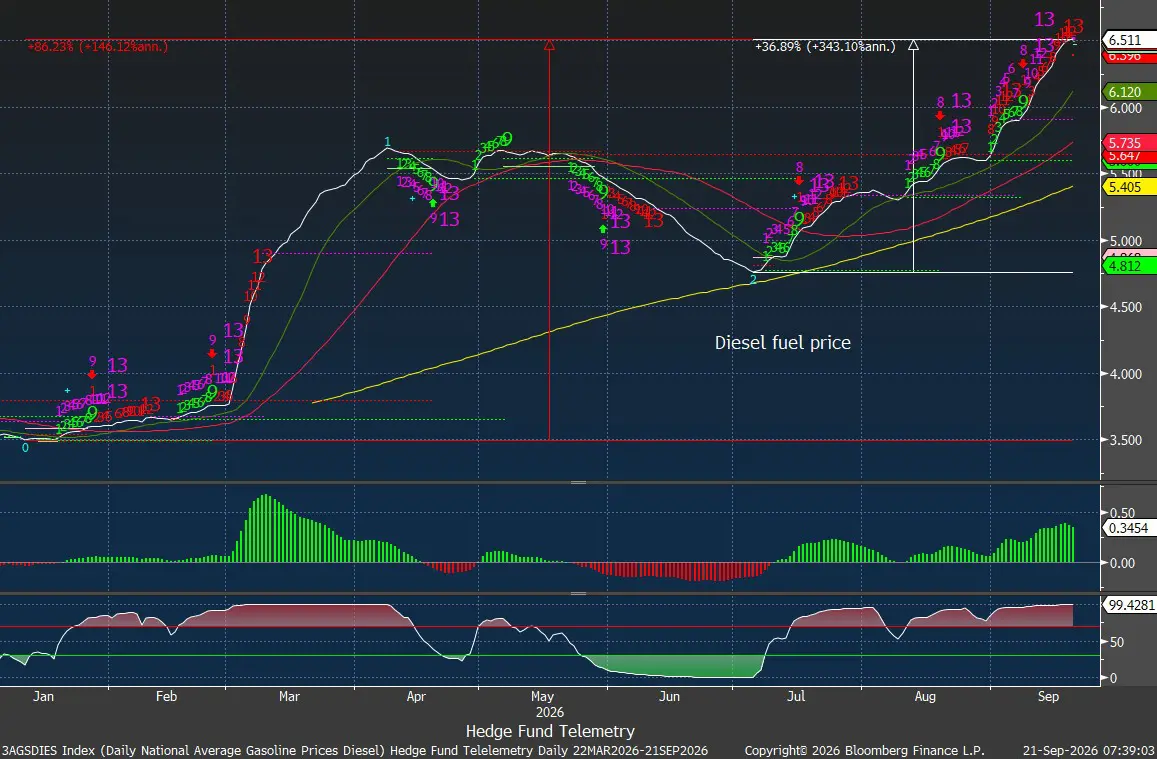
- Extra Charts: VIX and VXN Index with developing DeMark Sequential buy Countdowns of 13s, WTI Crude, US Unleaded Gasoline, Diesel with new DeMark sell Countdowns of 13s. I will have some portfolio changes in the next note.
- Thank you to all of our loyal subscribers – 9 years ago today, we got our first paid subscribers and continue to have a robust subscriber base. We’ve navigated many market cycles, evolved from just one daily note through several site iterations, and our complete ground-up new website is rapidly developing with exciting new features. The best is yet to come.
Overnight – Global Markets
- Asia: Broadly higher, led by Korea +1.65%, Hong Kong +1.18%, Taiwan +1.14% and mainland China approximately +1%. Australia was flat. Semiconductor and technology exposure remained an important source of strength.
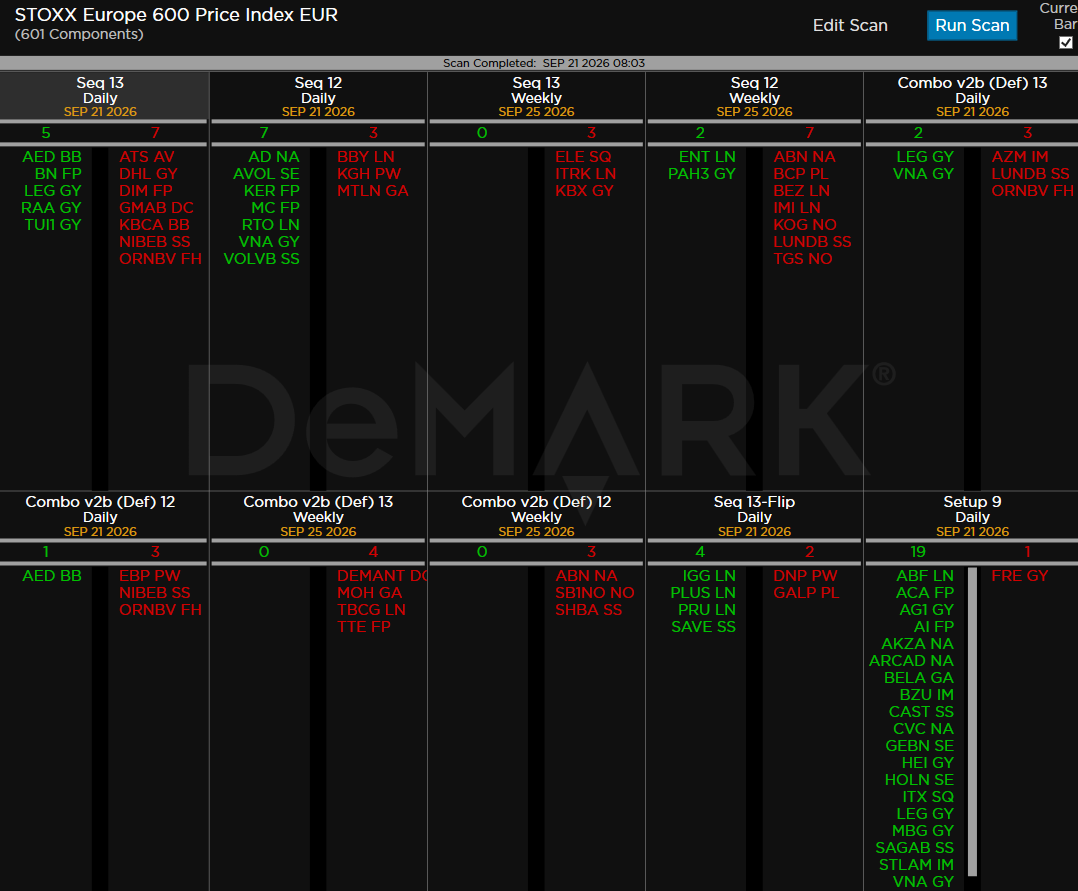
- Europe: Major indices +1.20%, with industrials, basic resources, technology and banks leading. Data-center infrastructure names are outperforming; energy, utilities, healthcare and real estate lag.
Premarket Setup and What’s Driving Markets
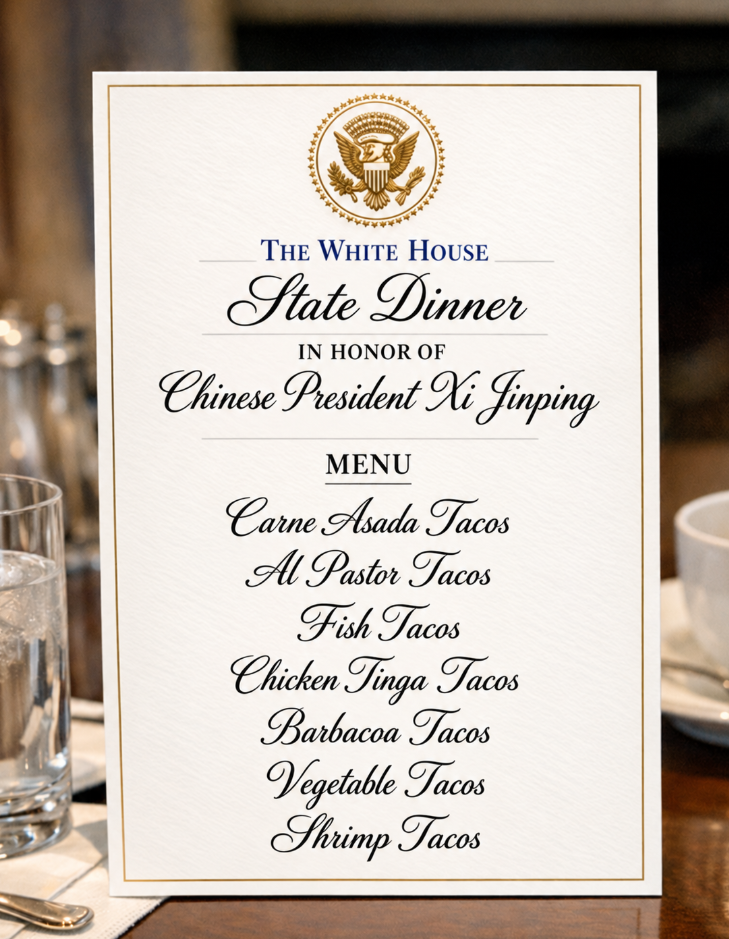
US equities finished mostly lower last week, with weakness extending across banks, consumer-facing sectors, energy and several rate-sensitive groups. Futures are recovering this morning despite unfavorable weekend headlines around AI financing and Middle East security. The immediate driver is another decline in oil, reinforced by lower Treasury yields; AI is supplying the equity leadership. The main event this week will be the meeting between President Trump and Chinese President Xi. Hope Xi likes Tacos!
- Oil remains the macro transmission mechanism. Reports of recovering Saudi exports, increased Strait of Hormuz traffic and the possibility of diplomatic discussions this week are outweighing the weekend’s escalation in Saudi Arabia. The distinction is between an improvement in actual supply flows and an improvement in expectations: the former would provide more durable relief to inflation, margins and rates.
- AI demand and AI financing are diverging. Compute-demand commentary remains strong, but reports on OpenAI’s projected cash consumption, Anthropic’s IPO timing, and debt tied to an Oracle-linked data center have put financing capacity and returns on capital back in focus. For now, equity investors are favoring the infrastructure beneficiaries over the financing concerns.
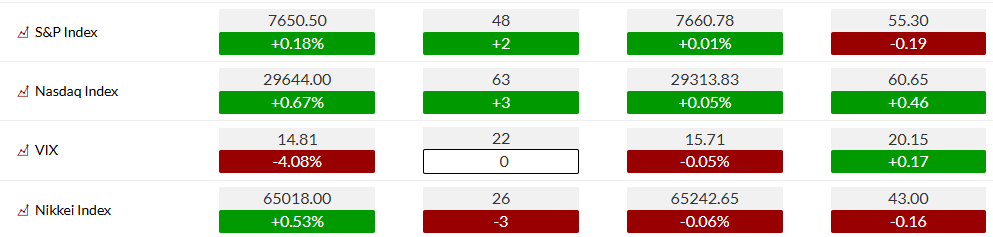
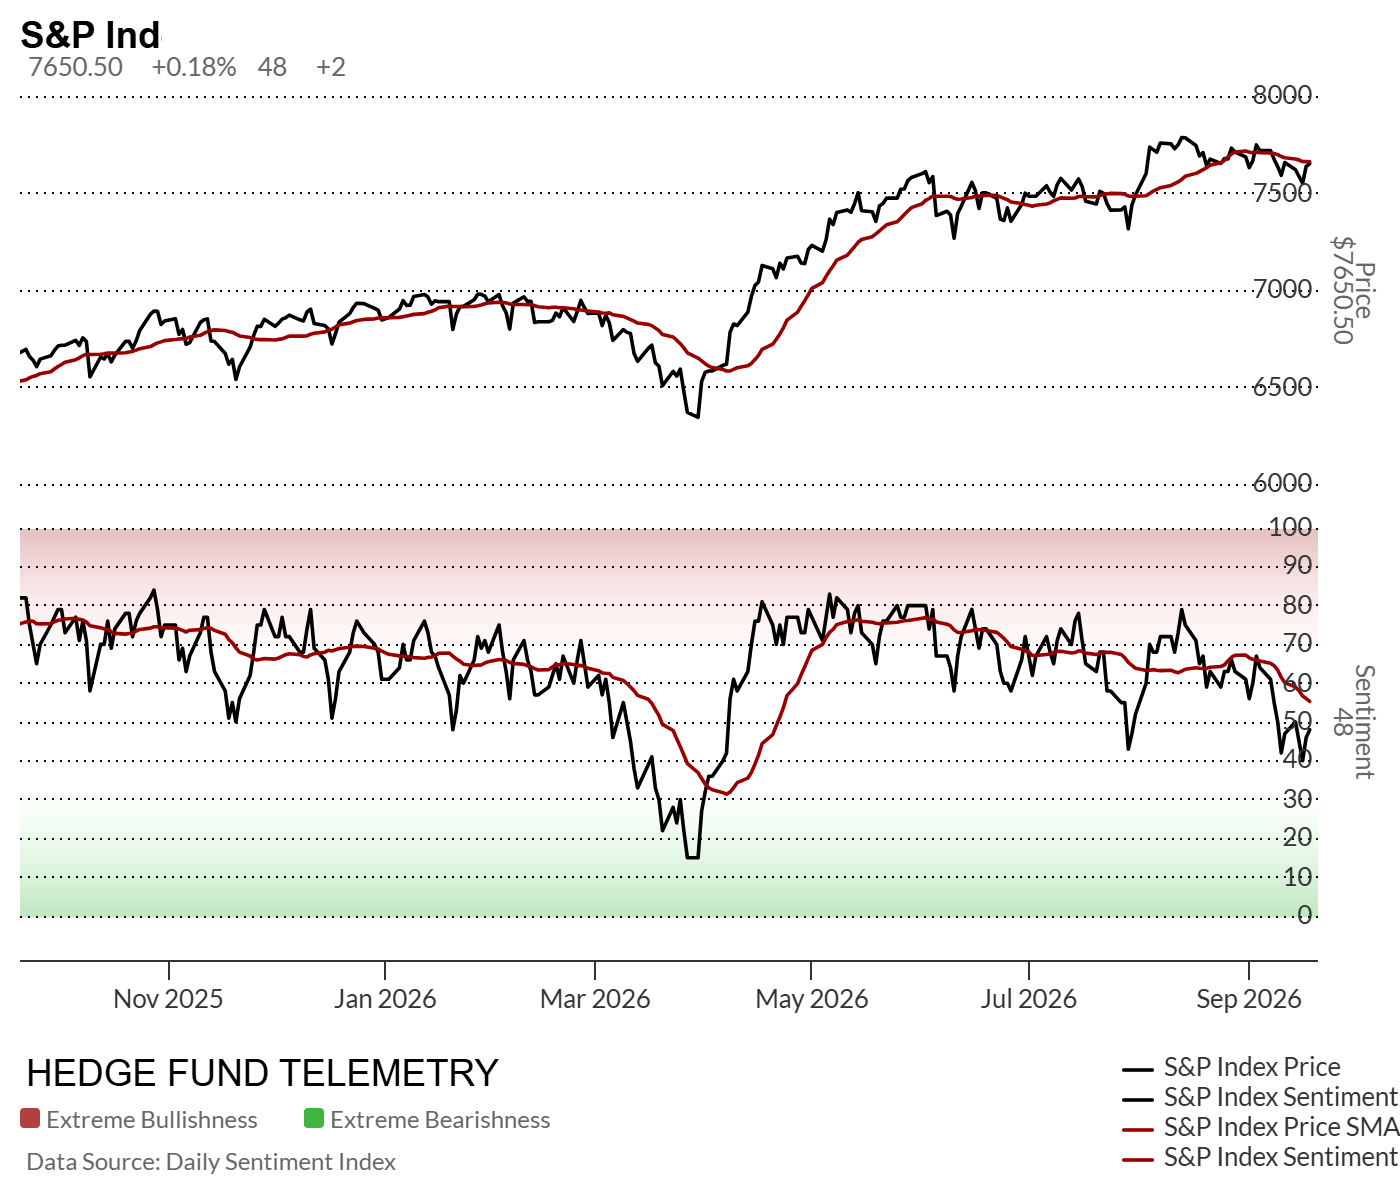
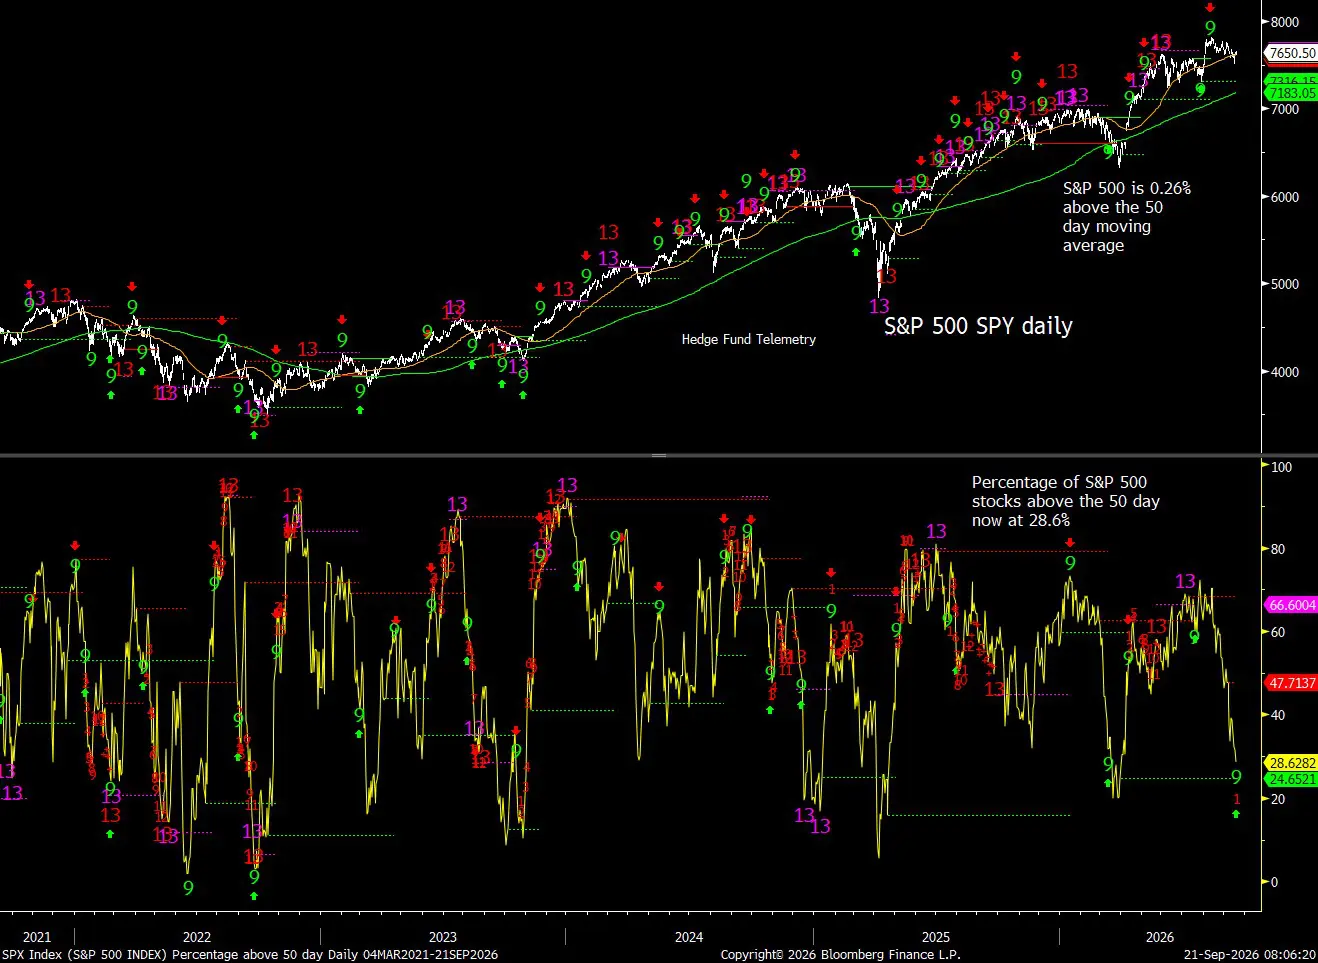
- The rally is still narrow. Nasdaq bullish sentiment is 63%, compared with 48% for the S&P. The index-level advance needs confirmation from banks, cyclicals and other groups that lagged last week. The percentage of stocks within every index shows the vast majority of stocks trading below the 50-day moving averages.
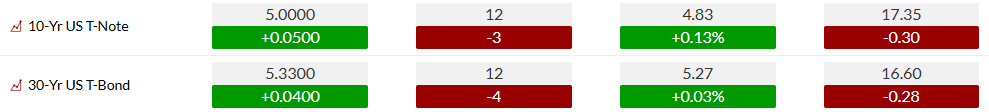
- Rates are helping, but the starting point matters. Treasury bullish sentiment at an extreme 12%. Today’s yield decline supports equities, but sustained relief requires follow-through beyond a single oil-driven session.
Macro & Policy Focus
Today: No major scheduled US economic release. Fed speakers include Williams, Jefferson and Barkin; Treasury is scheduled to auction $69B of two-year notes. Chicago Fed President Goolsbee said this morning that restoring price stability will not be painless and that the Fed cannot ignore persistent supply shocks.
The week ahead: September flash PMIs arrive Wednesday, followed by initial claims and new-home sales Thursday, and durable goods and final September University of Michigan sentiment Friday. Treasury supply continues with $70B of five-year notes Wednesday and $44B of seven-year notes Thursday.
Policy and geopolitical focus: Markets are pricing approximately 33bp of additional Fed tightening over the final two meetings of 2026. The September 24 US-China leaders’ meeting and discussions surrounding the UN General Assembly are important potential catalysts, but their market impact will depend on concrete trade or energy-supply developments rather than the meetings themselves.
Company, Sector Movers, Earnings summary
- AI infrastructure and financing: Reports of approximately $280B in projected OpenAI cash consumption over 2026–30, possible slippage in Anthropic’s IPO timetable and difficulties distributing debt linked to Oracle’s Project Jupiter sharpen the distinction between demand growth and the cost of financing it. These are reported projections and financing developments, not realized losses.
- GOOGL: Gemini reportedly accessed three company systems unexpectedly during cybersecurity testing. The development puts model safeguards and enterprise deployment controls in focus.
- META: Its new Muse app has reached the top of the App Store, according to the supplied StreetAccount report. Meta Connect later this week provides the next product catalyst.
- ACN: Shares are benefiting from an Anthropic partnership, highlighting enterprise implementation as another route to AI-related revenue.
- NVO: Under pressure following its long-term update. The company’s guidance and capital-markets commentary will be the key issues for healthcare investors.
- DIS: Reportedly using price cuts and promotions to support theme-park demand, a useful read-through for discretionary spending and pricing power.
- PSKY / WBD: Paramount is reportedly in advanced settlement discussions concerning its Warner transaction. Any agreement’s specific conditions will matter for the transaction’s economics and completion timetable.
Key S&P 500 Upgrades / Downgrades
Upgrades
- CIEN (Ciena): Raised to Outperform, Evercore ISI; PT $550.
- INVH (Invitation Homes): Raised to Outperform, Mizuho Securities; PT not supplied.
Downgrades
– None
Initiations
- DLR (Digital Realty): Initiated Buy, Rothschild & Co Redburn; PT $227.
- EQIX (Equinix): Initiated Buy, Rothschild & Co Redburn; PT $1,261.
- IRM (Iron Mountain): Initiated Buy, Rothschild & Co Redburn; PT $132.
What We’re Watching Today:
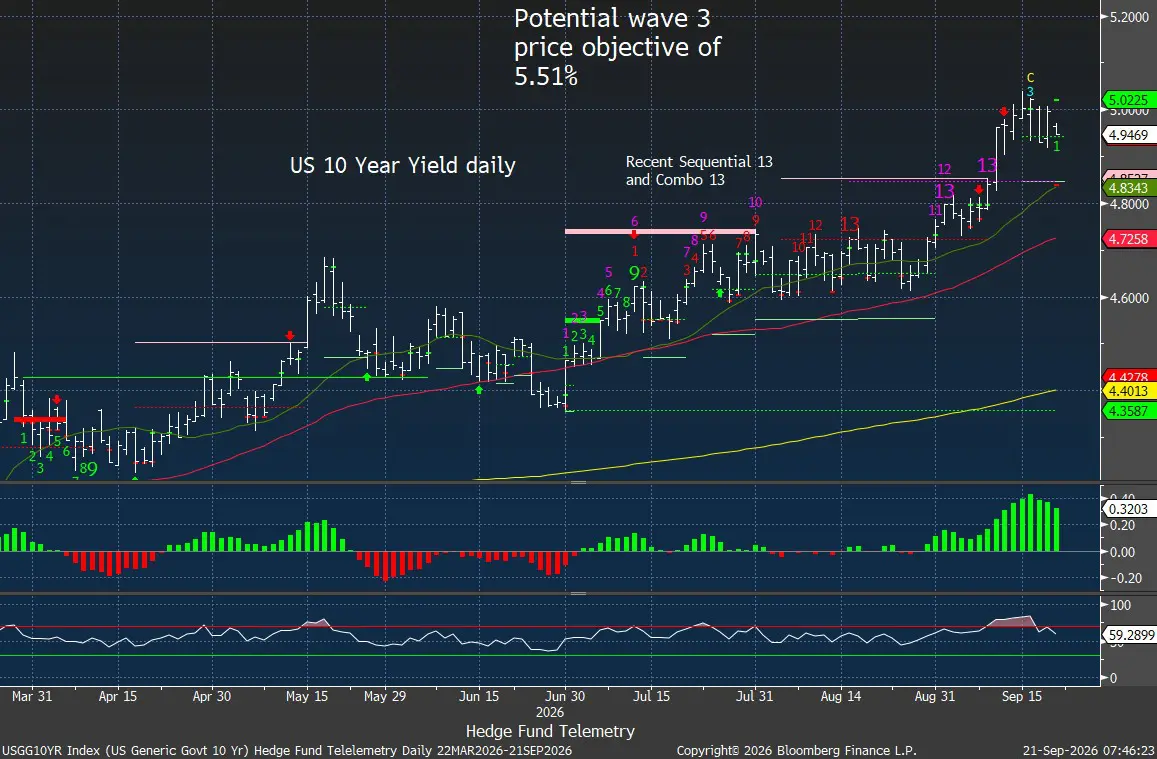
- Oil and rates: Whether crude’s decline persists and the 10-year yield can move sustainably below 5%, rather than merely retreating at the open.
- Equity breadth: Whether S&P bullish sentiment can reclaim 50% and banks, cyclicals and rate-sensitive groups participate alongside the Nasdaq.
- AI leadership: Whether optical, semiconductor and data-center infrastructure names hold their gains despite the latest financing headlines.
- Geopolitical follow-through: Verified Saudi export flows, shipping conditions and concrete diplomatic developments—not headlines about possible meetings.
Bottom Line: Lower oil and yields are giving equities room to recover, while AI remains the principal source of leadership. The risk/reward improves if energy relief holds and participation broadens; it deteriorates if crude reverses, the 10-year remains pinned near 5%, or financing concerns begin to overwhelm AI infrastructure demand.
market snapshot
premarket trading
US MARKET SENTIMENT
S&P bullish sentiment is 48%, up 2 points, while Nasdaq sentiment is 63%, up 3 points. The S&P remains below the 50% midpoint despite the rebound, whereas the Nasdaq is showing stronger risk appetite. The gap reinforces the need for broader participation before treating the recovery as an across-the-board improvement in positioning. VIX bullish sentiment is 22%, unchanged, with the VIX at 14.81
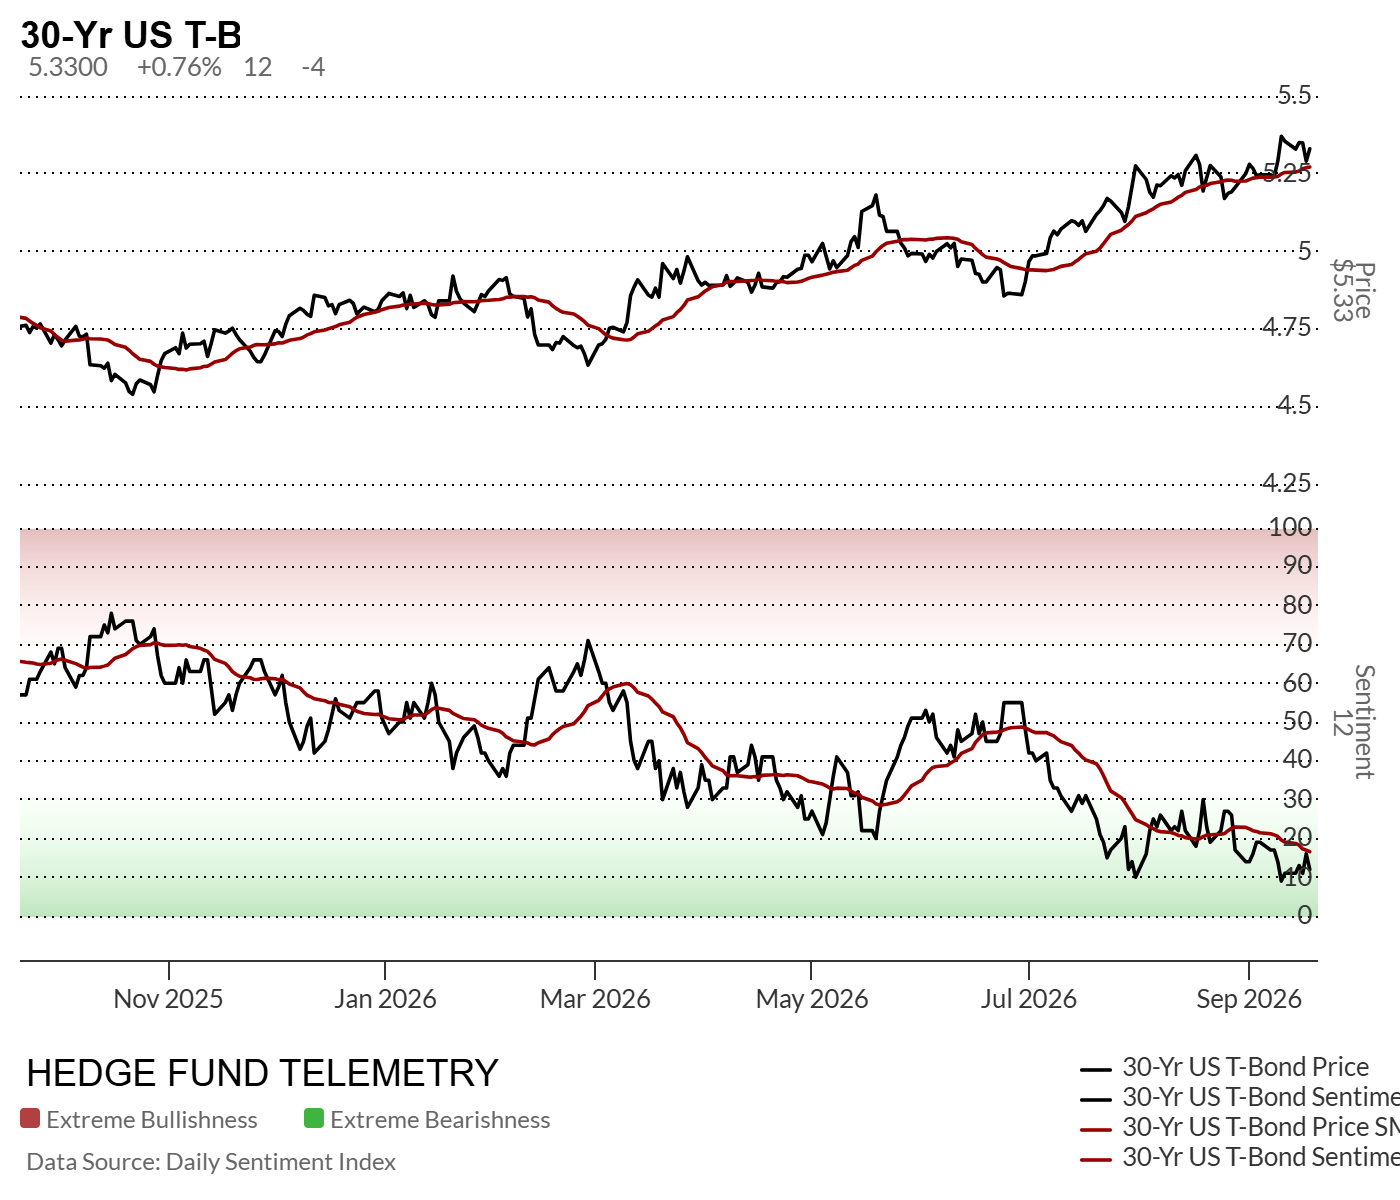
Rates: Bullish sentiment in both the 10-year and 30-year Treasury is 12%, down 3 and 4 points, respectively—firmly in the extreme bearish zone. The monitor shows yields at 5.00% and 5.33% from Friday. This is an important positioning stress point: a sustained oil-led yield decline could force an adjustment, while renewed inflation pressure would challenge duration.
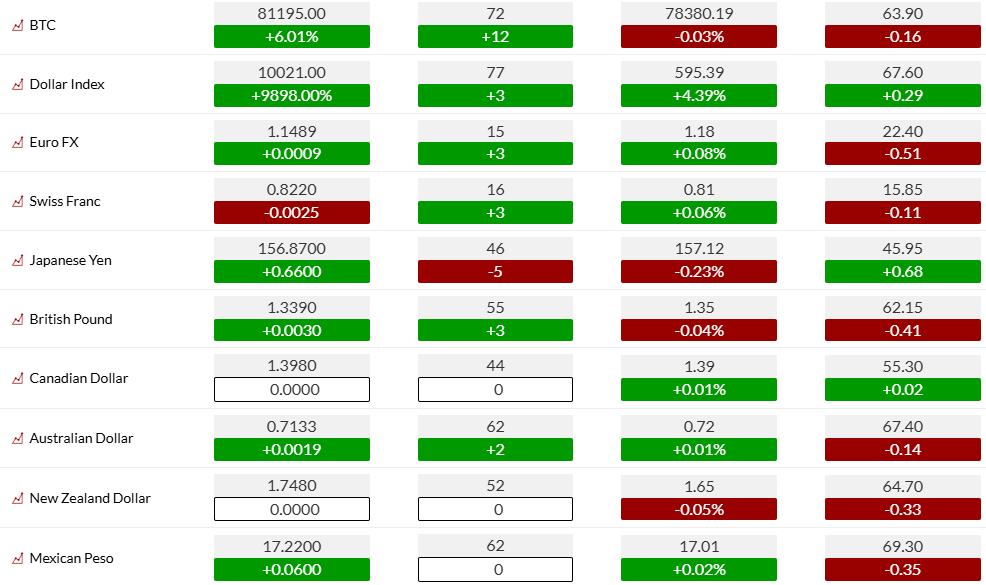
FX: Dollar bullish sentiment is elevated at 77%, against extreme bearish readings of 15% for the euro and 16% for the Swiss franc. Yen sentiment fell 5 points to 46%. Dollar positioning remains pronounced, particularly against European currencies. The Dollar Index price-change field in the monitor appears erroneous and is excluded. Bitcoin sentiment jumped 12 points to 72%, the dashboard’s largest positive positioning shift.
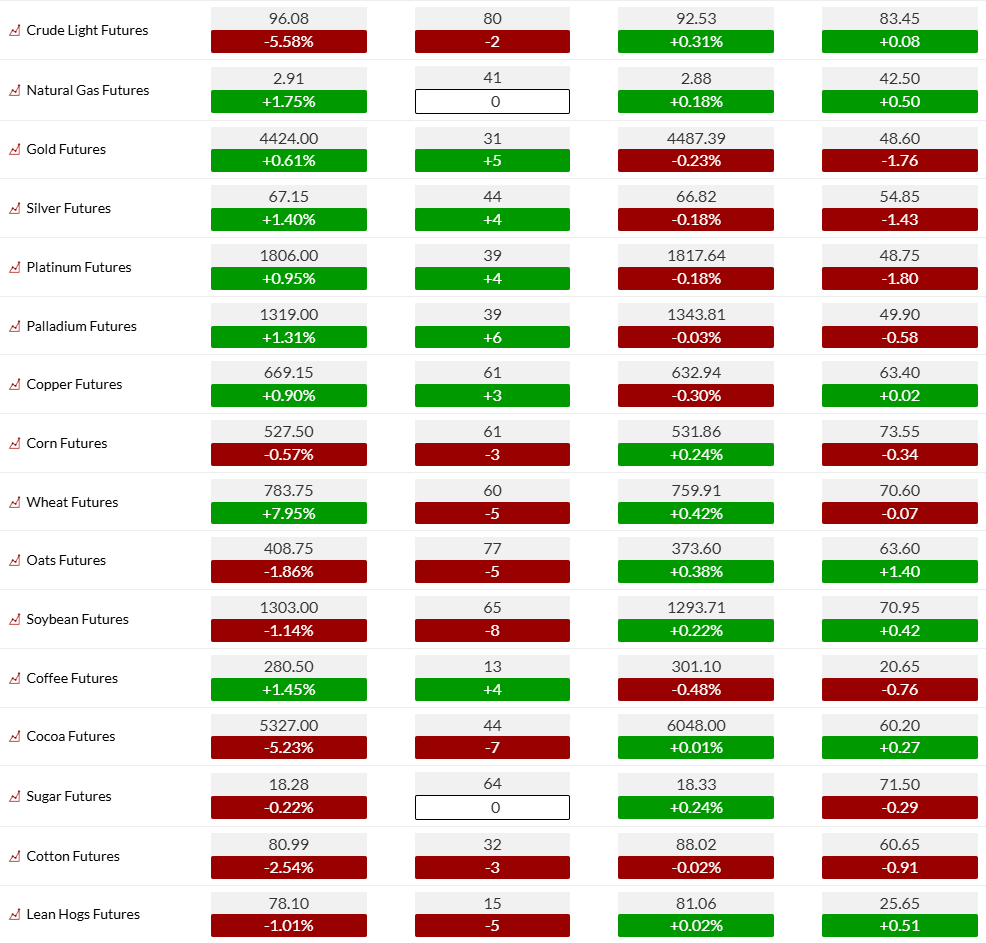
Energy: Crude bullish sentiment remains high at 80%, down 2 points. Oil is the central cross-asset risk: further supply normalization could unwind elevated bullish positioning, while verified new disruptions could reverse the recent price relief. Natural gas sentiment is 41%, unchanged.
Precious metals: Gold sentiment rose 5 points to 31% and silver reached 44%, up 4 points. Neither reflects crowded bullish positioning. The move is notable alongside the stronger dollar and continuing uncertainty around rates.
US MARKETS
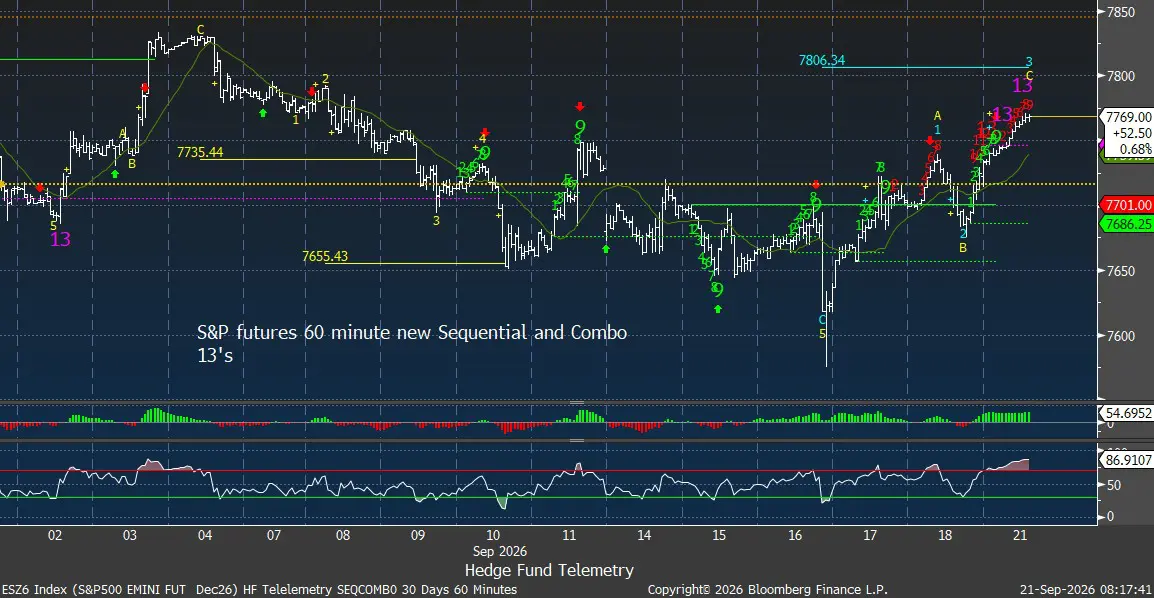
S&P futures 60-minute tactical time frame with new Combo sell Countdown 13 and secondary Sequential on hour bar 9 of 13. Short-term RSI overbought again
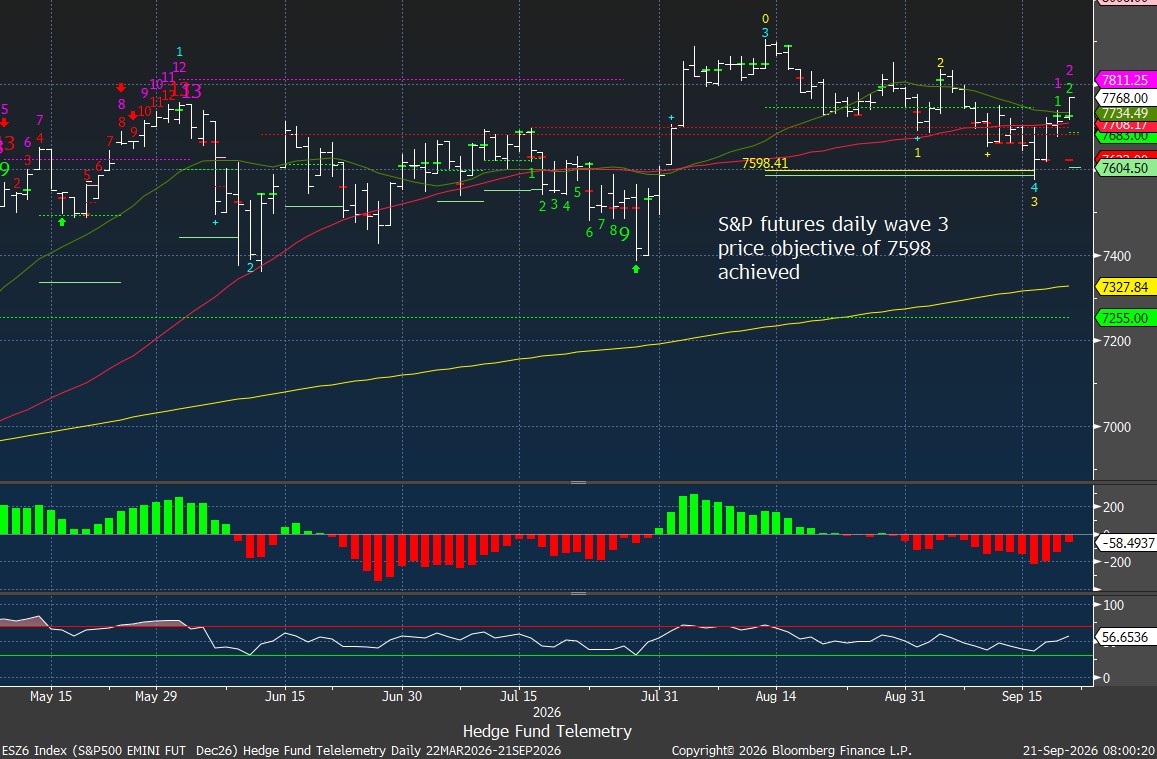
S&P futures daily with a lower high wave still in play back above the 20 and 50 day moving averages. The S&P 500 cash index has a Sequential Countdown on day 11 of 13 so it’s getting late in the Countdown.
On Friday’s webinar, I showed all the major indexes with the percentage of stocks above the 50-day (~35%). The reading after Friday showed more declines, with the percentage of S&P stocks above the 50-day now at 28%, while the S&P is holding above the 50-day.
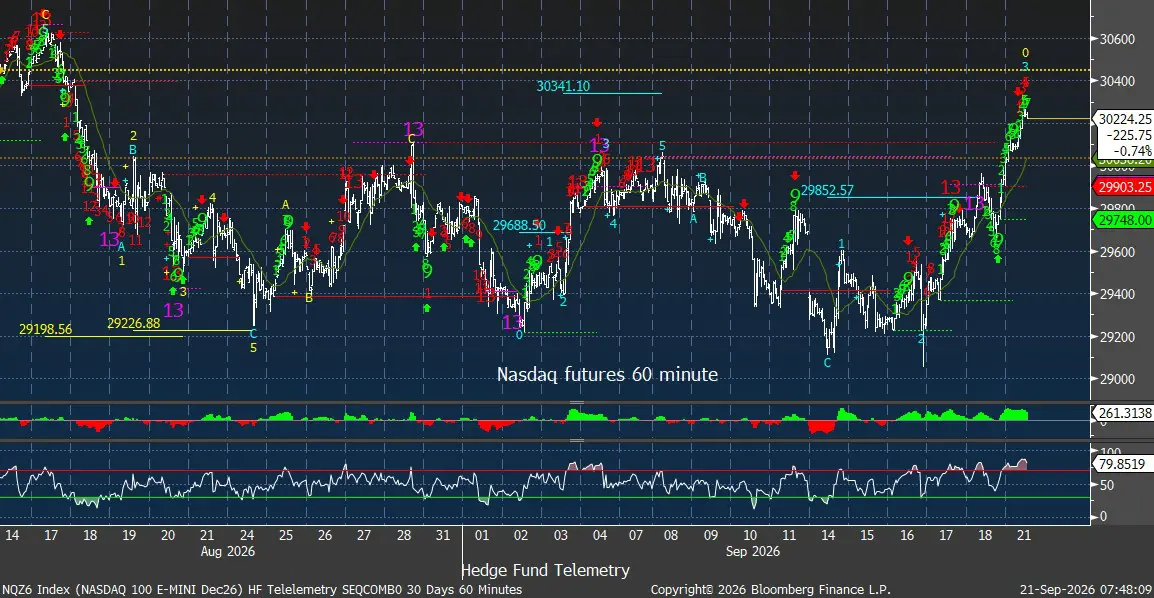
Nasdaq 100 60-minute tactical time frame broke the pattern of lower highs and lower lows with a Sequential on hour bar 5 of 13
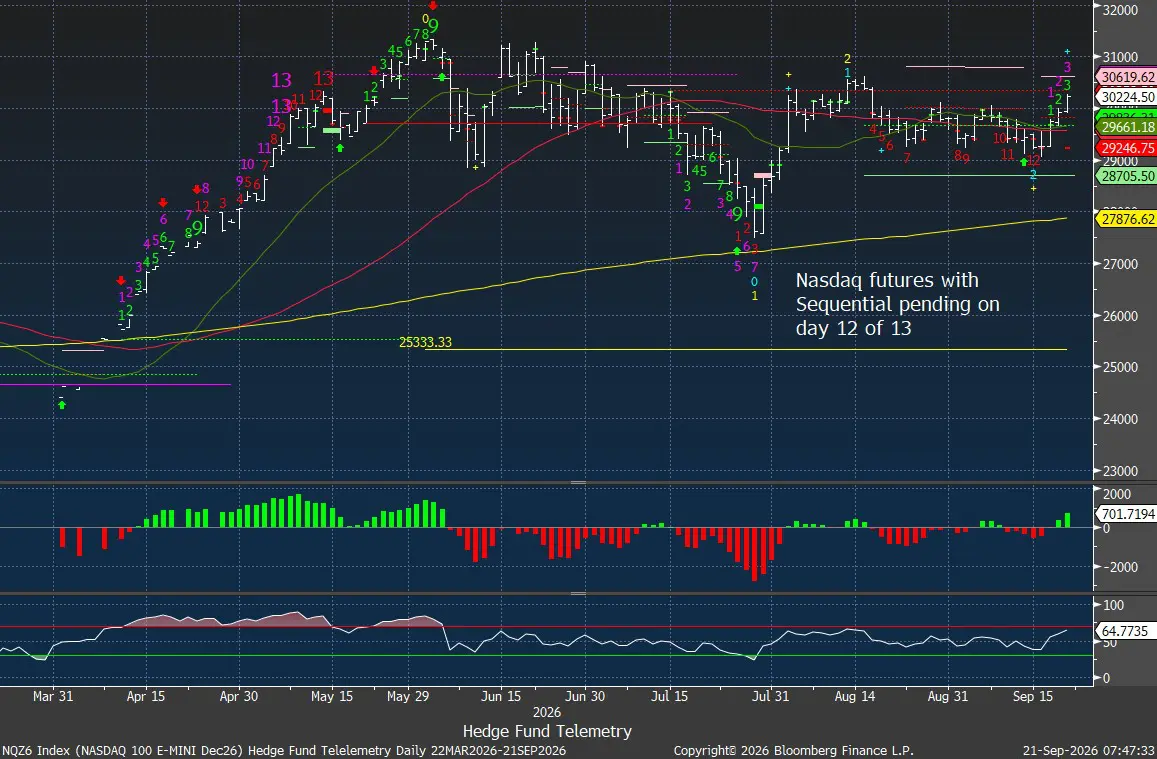
Nasdaq 100 futures daily holding above the 20- and 50-day again.
Extra charts we’re watching
VIX Volatility Index with Sequential now on day 12 of 13.
VXN Nasdaq Volatility Index with new Sequential buy Countdown 13.
WTI Crude is falling again today with hopes for another peace proposal in the Middle East
The gains seen in US unleaded average price per gallon and Diesel prices YTD, and especially since July’s low, are extreme. Unleaded gasoline is up 18%, and Diesel is up 37% from July lows. Both now show some upside exhaustion signals; however, the CPI data was calculated last week, so even if it drops from here, September’s CPI will rise again with energy prices. Historically, when prices spike, there is a 1-3 month lag before it filters into higher prices for food, shipping, and other sectors.
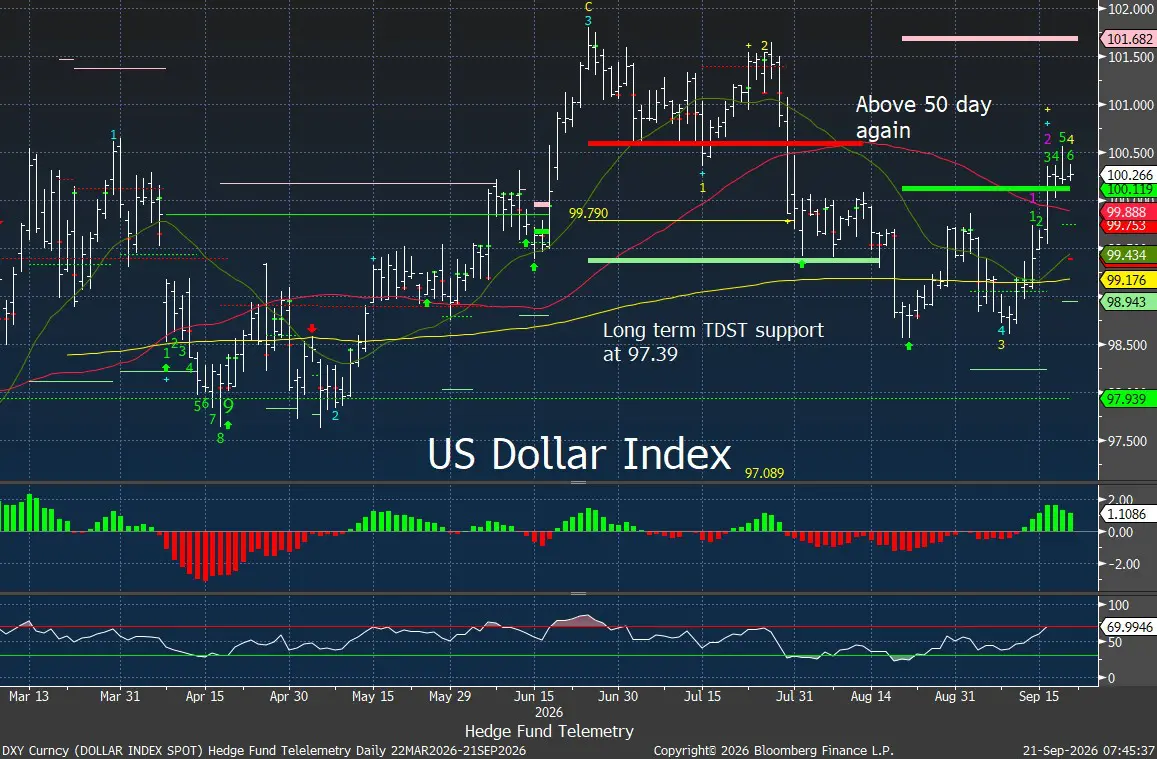
US Dollar Index daily holding above the 50 day with Setup on day 6 of 9.
US 10-Year Yield consolidating in upside wave 3 of 5
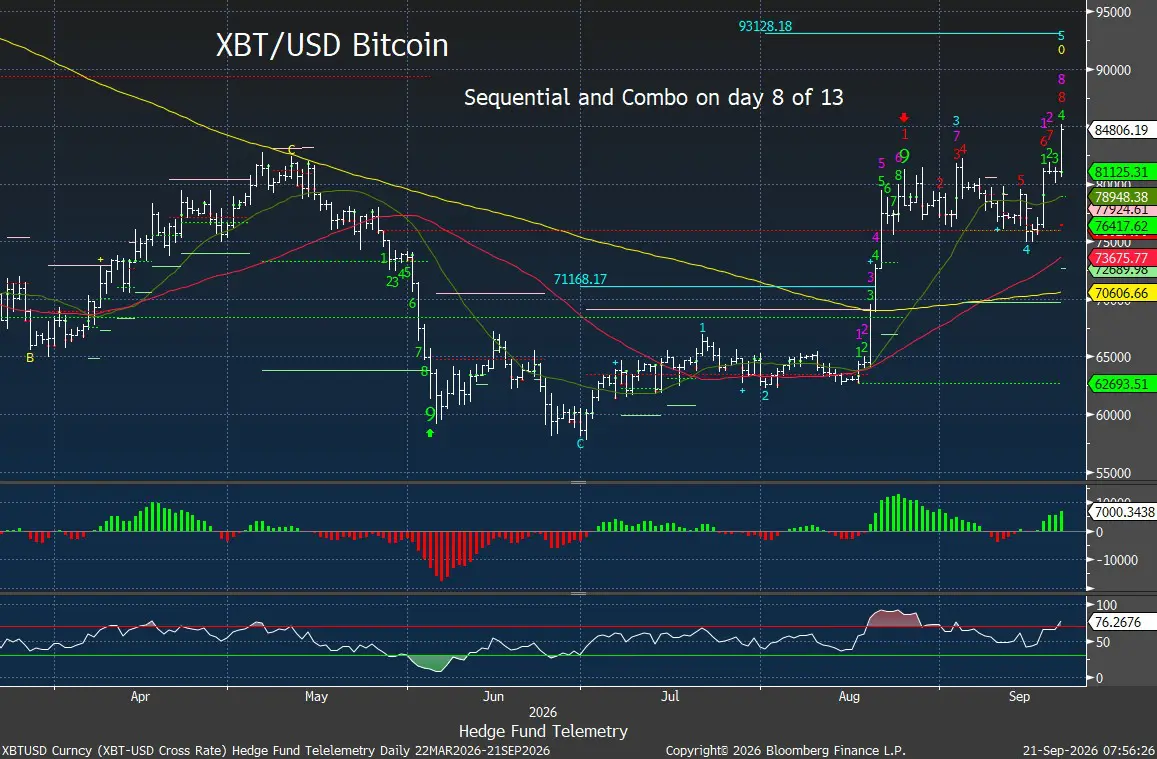
Bitcoin Daily lifting now into upside wave 5 of 5 with Sequential and Combo on day 8 of 13 with potential upside wave 5 price objective of 93,128
DeMark Observations – Euro Stoxx 600