
Market Setup
The coming week ahead is the most catalyst-heavy of the quarter, with peak Q3 earnings, three major central bank decisions (all expected to show no rate changes), US GDP and PCE inflation, and several important AI-related corporate events. The combination comes at a particularly vulnerable point for markets, with crowded technology positions under pressure, AI financing concerns intensifying, and investors increasingly questioning the sustainability of the capital spending cycle.
The constructive development has been rotation rather than outright liquidation, with equal-weight equities recently outperforming the major capitalization-weighted indices. However, sharply deteriorating equity sentiment and rising demand for Treasuries suggest risk appetite remains fragile. The key question is whether strong hyperscaler earnings can stabilize technology leadership or whether capital continues rotating toward less-crowded areas of the market.
Liquidity and positioning could become particularly challenging around Wednesday’s FOMC decision and the concentration of mega-cap earnings Wednesday and Thursday evenings. This is a week to prioritize reaction over anticipation.
We plan to launch the new website next weekend. We will send an email this week with details on what you need to do, which should mostly be changing your password. We anticipate a few issues once live, and we’ll resolve them quickly. Moving to a new platform, new email delivery is a big upgrade, so please thank you in advance for your patience. A few things to note: Pricing: For longer-term subs, we will continue to grandfather your $750 annual rate vs. the standard $1000 rate. If you cancel and still have time left on your subscription at the $750 rate, your grandfathered status will end unless you reach out before the site launch to continue at that rate. Our costs have gone up, especially with the new site’s new features and Bloomberg/DeMark price increases. We have done our best to keep rates steady and have offered discounts on occasion over the years, which we will not be doing this year. Instead, we will offer a new 2-year subscription plan at a discounted rate of $1,500, saving $500. Log-on and password sharing: Thanks to AI, we can track and identify those who share log-on information with friends. It’s not fair to us, and take note: we won’t warn users before shutting them off. We have had a sticky subscriber base and continue to grow thanks to many of you who have referred us to your friends. The next chapter is ahead, and I couldn’t be more proud of what we have created. Thank you.
Key Catalysts for the Week Ahead
Market Structure
- AI positioning and financing: Recent pressure on technology shares reflects growing concerns about capital availability, valuations, and the duration of the AI investment cycle. Strong demand alone is no longer sufficient; investors increasingly want evidence of monetization, sustainable margins, and cash generation.
- Mega-cap leadership: GOOGL, MSFT, and AMZN will be critical tests of whether the largest platforms can maintain investor confidence despite rapidly expanding capital budgets. Their financial flexibility provides an advantage over smaller, externally financed AI infrastructure companies.
- Rotation versus broader risk reduction: Watch whether equal-weight equities, financials, industrials, and other previously overlooked sectors continue outperforming. Failure of that rotation alongside further technology weakness would be a more concerning development. See charts below.
- Treasury hedge: The recent sharp decline in Treasury rates during equity weakness suggests duration is regaining some defensive characteristics despite elevated inflation and energy prices.
- New Short Interest Data: Released Monday after the close for the October 15th close. Watch this alongside recent market moves, especially in tech. I can’t wait for you all to access our new single-stock positioning feature.
Macro Data
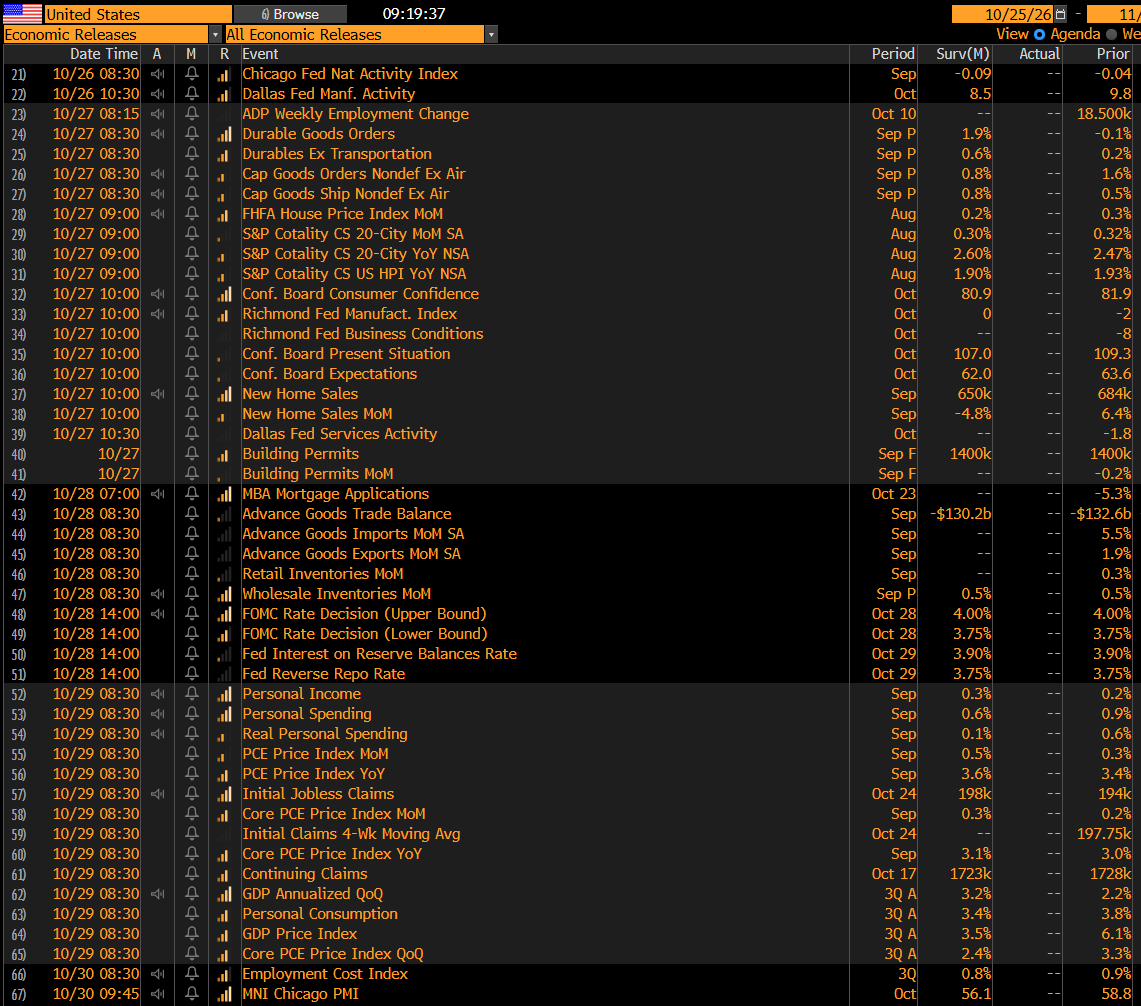
- Q3 GDP: Growth expected to accelerate to 3.0% annualized from 2.2% in Q2. A strong reading would reinforce the economic resilience narrative but potentially support higher rates.
- September PCE: Headline inflation expected to accelerate 20 basis points and core inflation 10 basis points. The combination of stronger growth and sticky inflation could complicate expectations for monetary policy.
- Employment Cost Index: Friday’s release will provide another important indication of underlying wage pressures.
- Consumer confidence and durable goods: Secondary indicators worth watching for evidence of slowing demand or continued business investment strength.
Central Banks / Policy
- Federal Reserve – Wednesday: Rates widely expected to remain unchanged, with market pricing indicating approximately 90% probability of a hold. The focus will be on the December meeting, where markets still assign greater than 80% probability to a hike. Any dissent or change in the Fed’s assessment of growth and inflation could have a meaningful impact on rates.
- ECB – Thursday: No change expected. Weak European activity and ongoing French sovereign debt concerns complicate the policy outlook.
- Bank of Japan – Thursday night: No change expected, although persistent inflation reinforces expectations for tightening later this year. Yen positioning and global carry trades remain potential catalysts for volatility.
- UK Budget: Markets will closely scrutinize fiscal plans and borrowing assumptions against elevated sovereign financing costs.
Geopolitics
- Israel election – Tuesday: Gadi Eisenkot holds a modest polling and prediction-market advantage over Benjamin Netanyahu. The outcome could influence expectations for regional military operations, diplomatic negotiations, and energy markets.
- Middle East: Renewed military activity remains a significant risk, particularly with crude sentiment already in extreme bullish territory.
- European sovereign risk: France remains a potential source of financial market contagion, particularly if political instability pushes borrowing costs higher.
Sector-Specific or Idiosyncratic Risks
- Oracle AI World: Wednesday’s presentations will be scrutinized for new information on AI infrastructure demand, financing, and capacity commitments. NVDA’s participation adds importance to the event.
- Apple: Wednesday’s Pro & Tell event will provide updates on new phones and product positioning.
- SpaceX / Wireless: Potential tower leasing agreements and Starlink Mobile expansion create new competitive risks for traditional wireless carriers.
- Healthcare: Several regulatory decisions, including MRK’s ILUMYA, INO-3107, and AGIO’s PYRUKYND, alongside major pharmaceutical earnings.
- Corporate events: FFAI Investor Day Monday; healthcare events from BOLT, MRK, CPIX, LBRX, and ZBIO; utility-related events involving BEP, ETR, and EXC.
Earnings Calendar
Monday, October 26
Pre-Market: VZ – Verizon.
Post-Market: AMKR – Amkor; ARE – Alexandria Real Estate; CDNS – Cadence Design Systems.
Tuesday, October 27
Pre-Market: BA – Boeing; FCX – Freeport-McMoRan; GLW – Corning; HCA – HCA Healthcare; HLT – Hilton; HUBB – Hubbell; ITW – Illinois Tool Works; KO – Coca-Cola; PYPL – PayPal; RCL – Royal Caribbean; UPS – United Parcel Service.
Post-Market: NXPI – NXP Semiconductors; SKHY – SK Hynix; STX – Seagate; TER – Teradyne; V – Visa.
Wednesday, October 28
Pre-Market: ADP – ADP; APH – Amphenol; BIIB – Biogen; BSX – Boston Scientific; EAT – Brinker; ETSY – Etsy; FLEX – Flex; GEHC – GE HealthCare; GEV – GE Vernova; GNRC – Generac; LII – Lennox; OTIS – Otis; TEL – TE Connectivity; VRT – Vertiv.
Post-Market: CMG – Chipotle; CVNA – Carvana; EBAY – eBay; F – Ford; FDX – FedEx; FTNT – Fortinet; GOOGL – Alphabet; HONA – Honeywell Aerospace; KLAC – KLA; MGM – MGM Resorts; MSFT – Microsoft; NOW – ServiceNow; TMUS – T-Mobile; Samsung Electronics.
Thursday, October 29
Pre-Market: BMY – Bristol Myers Squibb; CARR – Carrier; CAT – Caterpillar; CTSH – Cognizant; EME – EMCOR; HWM – Howmet Aerospace; LLY – Eli Lilly; MA – Mastercard; MRK – Merck; NCLH – Norwegian Cruise Line.
Post-Market: AMZN – Amazon; COIN – Coinbase; GDDY – GoDaddy; MDLZ – Mondelez; RDDT – Reddit; SBUX – Starbucks; SNDK – Sandisk; TWLO – Twilio.
Friday, October 30
Pre-Market: ABBV – AbbVie; AN – AutoNation; CL – Colgate-Palmolive; CVX – Chevron; LYB – LyondellBasell; NVT – nVent; XOM – Exxon Mobil.
Key European / International Earnings
- Tuesday: HSBC; Novartis; Reckitt Benckiser; ASM International (post-market).
- Wednesday: Adyen; BASF; BNP Paribas; Danone; Deutsche Bank; GSK; Mercedes-Benz; Santander; Standard Chartered; Stellantis; UBS; Unilever; Airbus (post-market).
- Thursday: Adidas; Anheuser-Busch InBev; Lloyds Banking Group; Shell; Société Générale; STMicroelectronics; Volkswagen; Universal Music Group.
- Friday: AstraZeneca; BP; Sanofi.
Economic Calendar
Monday: No major US economic releases
Tuesday: Durable Goods Orders; FHFA House Price Index; New Home Sales; Consumer Confidence.
Wednesday: MBA Mortgage Applications; Wholesale Inventories; FOMC Rate Decision (2:00 PM ET).
Thursday: Q3 GDP; September PCE Inflation; Personal Income & Spending; Initial Jobless Claims (major US releases at 8:30 AM ET); ECB Rate Decision; BOJ Meeting (overnight).
Friday: Employment Cost Index (8:30 AM ET); Chicago PMI (9:45 AM ET).
Earnings Preview – What Matters
AI Hyperscalers / Software
- GOOGL: Cloud is the central focus, with growth expected near 90% and operating margins above 33%. Revenue ex-TAC expected +27% to $111.3B, while capex more than doubles to $55.7B, pushing expected FCF negative. The issue is no longer demand but whether the scale of spending can produce acceptable returns.
- MSFT: Azure growth expected +44%, with operating margins near 48% and EPS of $4.73. Capex projected at $51.8B. Microsoft’s platform dominance and financial resources make it relatively attractive within AI, although spending discipline and cash conversion remain important.
- AMZN: AWS expected to grow approximately 38% with 37% operating margins. Capex of $58.5B and expected negative FCF of $8.2B highlight the widening gap between strong cloud fundamentals and enormous infrastructure requirements.
- NOW / CTSH: Improving sentiment toward established software providers reflects reduced fears of AI displacement. NOW’s cRPO growth near 20% will be an important test of enterprise spending.
- RDDT: Revenue expected +49%, but US daily active user growth of just 3.75% and the status of its Google relationship are the critical variables.
- TWLO: Organic growth expected above 15%, with increasing optimism around AI agents driving demand for communications infrastructure.
Semiconductors / AI Infrastructure / Power
- AMKR / APH: Strong AI-related demand continues, but capex intensity and margins are the risks. AMKR capex expected to rise 265%, while APH organic growth is projected near 30%.
- GLW / FLEX / VRT: Optical, cloud infrastructure, and cooling demand remain strong, with expected growth of 34% in GLW optical, 51% in FLEX Cloud & Power, and 37% organic at VRT. The question is the duration of the buildout rather than near-term orders.
- GEV / CAT / CARR: Power generation, grid infrastructure, and commercial cooling remain favored areas of industrial exposure. GEV sales expected +20%, CAT backlog near $73.5B, and CARR organic growth accelerating to 11%.
- KLAC / NXPI: KLAC benefits from continued semiconductor investment but faces elevated expectations following LRCX’s underwhelming guidance. NXPI offers cheaper valuation and recovering growth, although China auto exposure remains a concern.
- SNDK: Sales expected +361% and EPS of $46.06. The debate is entirely about how long extraordinary memory profitability can persist, with valuations already reflecting significant skepticism about cycle duration.
- NVT / TEL: Continued data center infrastructure demand supports growth, although investors remain sensitive to any evidence of spending moderation.
Consumer / Financials / Travel
- V / MA: Both payment networks are expected to deliver double-digit revenue and EPS growth, supported by resilient spending and value-added services. Cross-border volumes and spending trends will provide important macro signals.
- PYPL: Valuation, buybacks, and FCF support the turnaround thesis, with TPV expected +7.2%. Transaction margins and execution remain the key tests.
- KO / MDLZ: Relative defensive strength within staples, with KO benefiting from pricing power and MDLZ from improving cocoa costs. Volume trends remain important.
- SBUX / CMG / EAT: SBUX comps expected +6.2% and Chili’s +7.6%, contrasting with CMG’s expected +1.3%. Restaurant traffic and margin performance should help distinguish company-specific execution from broader consumer weakness.
- HLT / RCL / NCLH: Travel demand remains resilient, but elevated fuel costs and uneven operating performance create significant differentiation. NCLH faces more company-specific challenges than RCL.
- VZ / TMUS: Wireless competition is intensifying, particularly with the potential emergence of Starlink Mobile. Subscriber additions, pricing, and FCF will matter more than headline revenue.
- BA / UPS / F: Boeing needs to demonstrate progress on production and FCF, UPS must sustain cost reductions amid difficult demand, and Ford faces continued EV losses and recall costs.
Healthcare / Energy / Industrials
- LLY: Revenue expected +27%, supported by continued GLP-1 leadership. Competitive pricing and market share remain the primary risks.
- MRK / BMY / ABBV: Patent exposure and pipeline execution remain central. ABBV’s Skyrizi and Rinvoq growth continues to offset legacy product declines, while MRK benefits from improving confidence around Keytruda.
- BSX: Expectations have reset following slowing Watchman and Farapulse momentum. Low expectations could help, but evidence of renewed growth is needed.
- CVX / XOM: Elevated crude prices, strong cash generation, and capital returns support the sector. Investors will focus on sustainability of refining and upstream margins.
- LYB: Geopolitical disruptions favor US feedstock economics, although underlying chemical demand remains weak.
Earnings takeaway: The largest earnings risk is concentrated in AI, where strong revenue growth is already expected, but tolerance for higher capital spending and weaker FCF has declined. Outside technology, payment networks, power infrastructure, and select healthcare companies offer important tests of whether market leadership can continue broadening.
Weekend Developments & Geopolitical Risk
Primary Geopolitical Themes
- Iran / Middle East: Escalation risks are rising materially. Trump is reportedly leaning toward another major round of strikes against Iran, with US warships preparing for renewed operations. Meanwhile, intelligence warnings of potential Iranian attacks on Americans have prompted reductions in US diplomatic personnel across the region. Saudi Arabia reopened Riyadh’s main airport following its closure from Houthi attacks, but the broader trajectory remains toward confrontation rather than de-escalation. The implications for crude, inflation expectations, and geopolitical risk premiums remain significant.
- France: Moody’s maintained France’s credit rating but kept its negative outlook, offering temporary relief without addressing the underlying fiscal and political risks.
Sector / Single-Stock News
- AI Infrastructure / Financing: AMZN says AWS capacity is largely sold out through 2027, with commitments extending into 2028, reinforcing strong underlying demand. However, Musk warned of stranded compute hardware in unfinished data centers as infrastructure construction struggles to keep pace with chip deliveries. Capex growth could slow if data centers are completed before Nvidia and other semiconductor hardware arrive. Amazon has said they have a lot of Nvidia hardware in storage because data centers aren’t complete. A risk to Nvidia. Meanwhile, SPCX reportedly struggles to finance its $40B Nvidia chip SPV. The disconnect between robust AI demand and increasingly constrained financing and infrastructure execution remains a central market risk.
- OpenAI / Anthropic: OpenAI has reportedly gained market share through aggressive pricing and improved models. Intensifying competition raises questions about pricing power, margins, and the ultimate returns on enormous AI infrastructure investments. Anthropic S-1 is expected this week with a $1.5 trillion valuation estimate down from the earlier $2 trillion level.
- M&A: CART Instacart is exploring a potential sale, with preliminary discussions involving DASH and UBER, although UBER talks are no longer active. Couche-Tard has offered $7.5–8B for Cumberland Farms, below the $9B valuation sought in its recently delayed IPO. The valuation discount reinforces a more selective environment for transactions and capital raising.
- JBLU: Senior creditors have engaged a restructuring advisor as elevated debt and surging fuel costs pressure the airline’s financial position. Another sign that sustained high energy prices are exposing leveraged business models.
Bottom Line: Thursday’s sharp technology selloff was accompanied by improving market breadth, suggesting rotation rather than indiscriminate risk reduction. However, the rapid deterioration in equity sentiment, increasingly restrictive AI financing conditions, and elevated geopolitical risks argue against assuming the correction is complete. These remain the two dominant risks entering the week. Strong AI demand is increasingly being offset by concerns about funding, infrastructure bottlenecks, and returns on capital, while the threat of renewed military action against Iran keeps energy and inflation risks elevated. With crude sentiment already at extreme bullish levels and equity positioning deteriorating, markets have limited room for disappointment heading into a catalyst-heavy week.
Charts we are watching
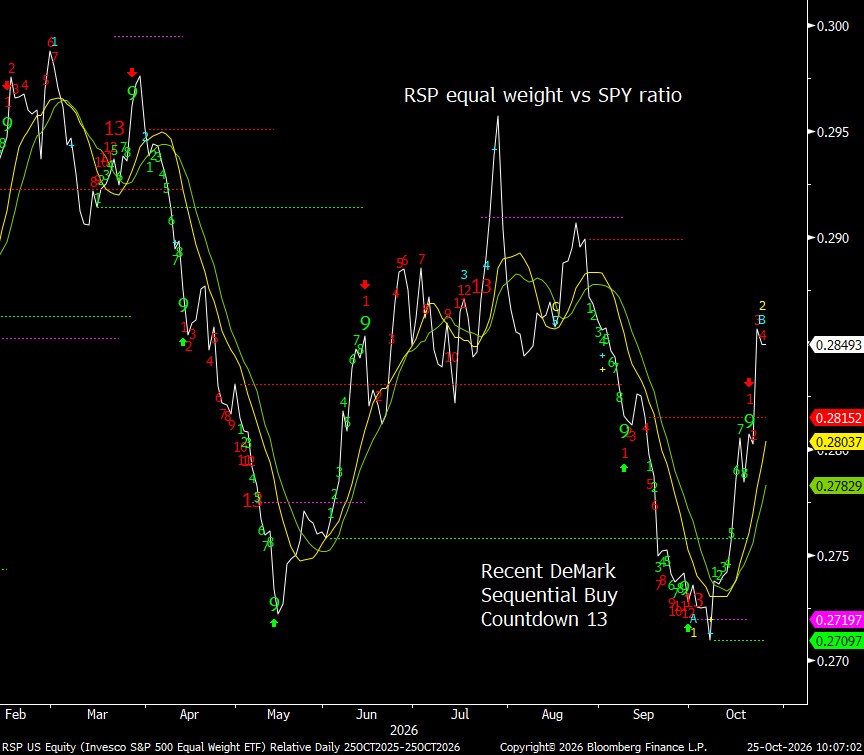
Recently, we highlighted this chart (and other ratio charts) showing the potential for broadening and/or Mag 7 gains to peak. This is the RSP S&P 500 equal weight vs the index-weighted SPY ratio.
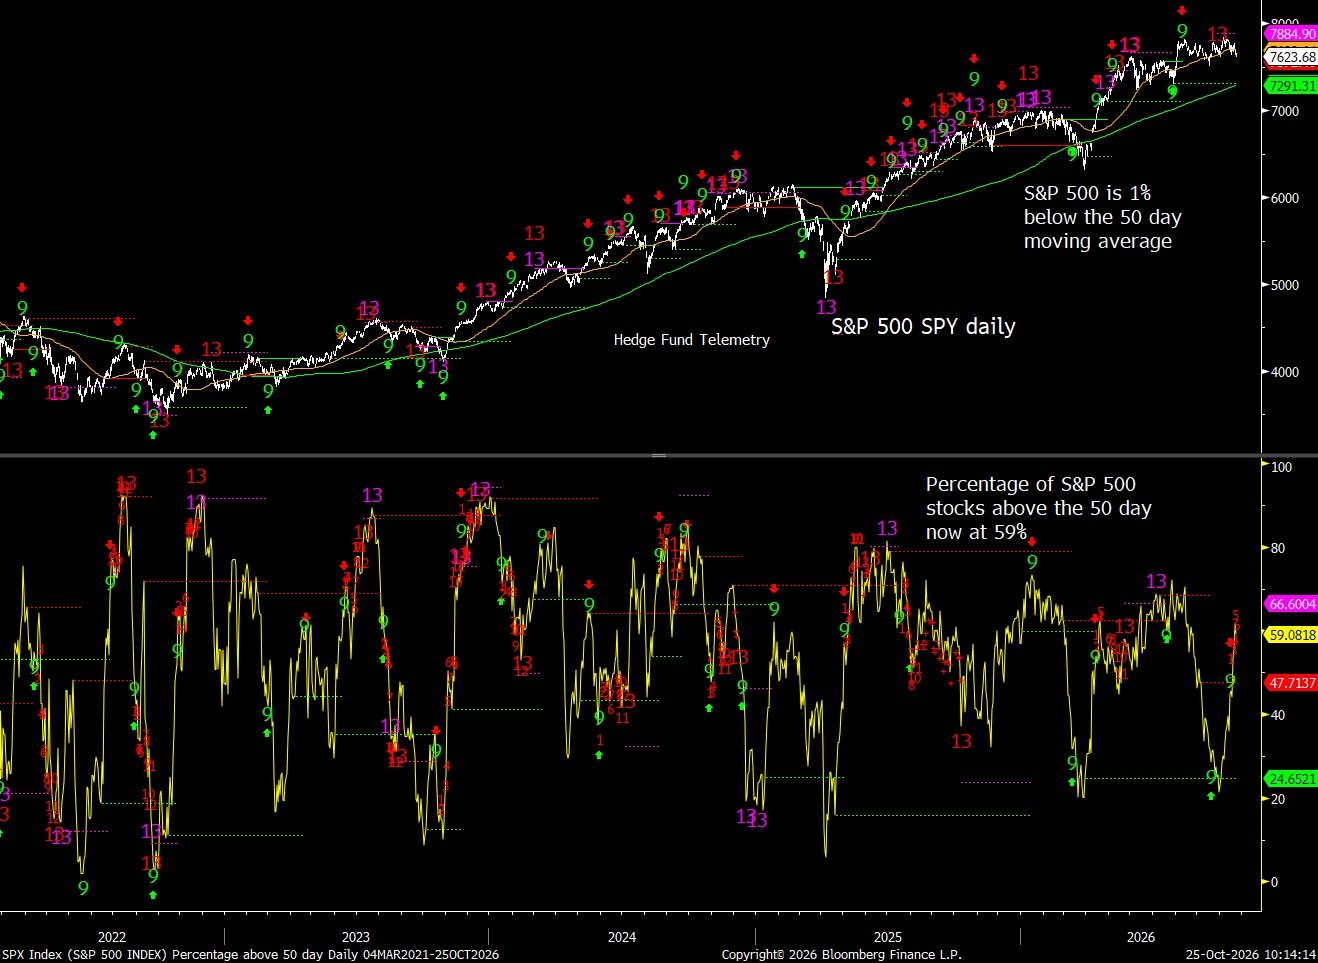
Another chart highlighted how the percentage of S&P stocks above the 50-day moving average fell to 24%, while the S&P was still above the 50-day moving average. Now the S&P is 1% below the 50-day, and 59% are above the 50-day. This is a positive sign of rotation and broadening. It comes at a time when sentiment for the indexes has been dropping, with risk of the AI narrative stocks breaking down further (see NDX chart from yesterday with potential new downside Sequential starting)
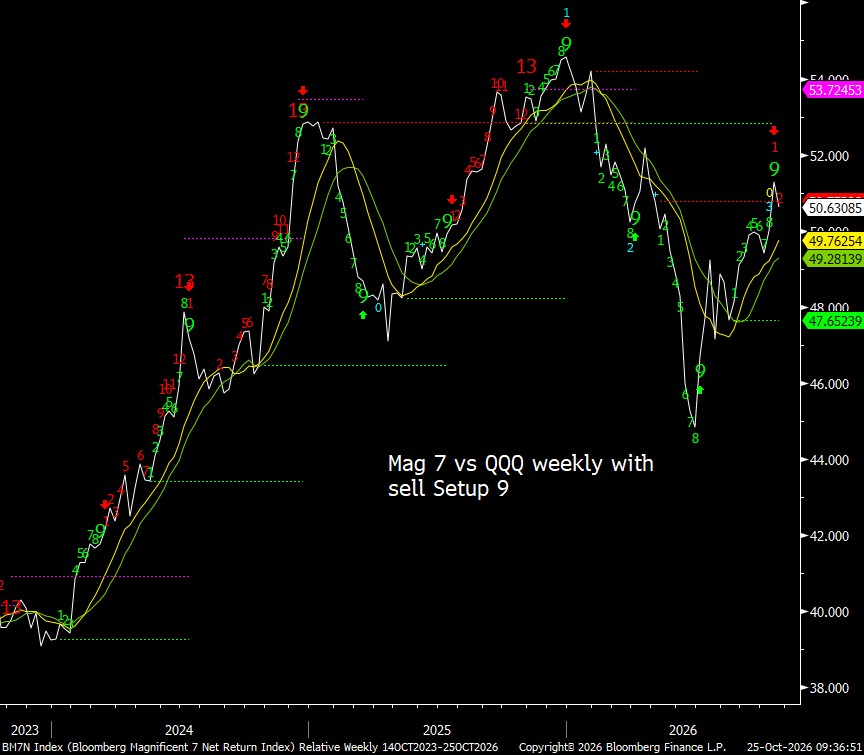
The weekly chart of the Mag 7 vs. QQQ ratio shows some stalling over the last two weeks. The RSP vs. SPY daily ratio may be more informative now.
US economic data for the week
KEY MARKET SENTIMENT
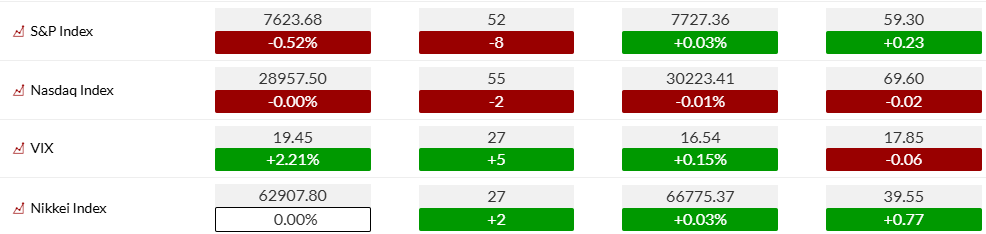
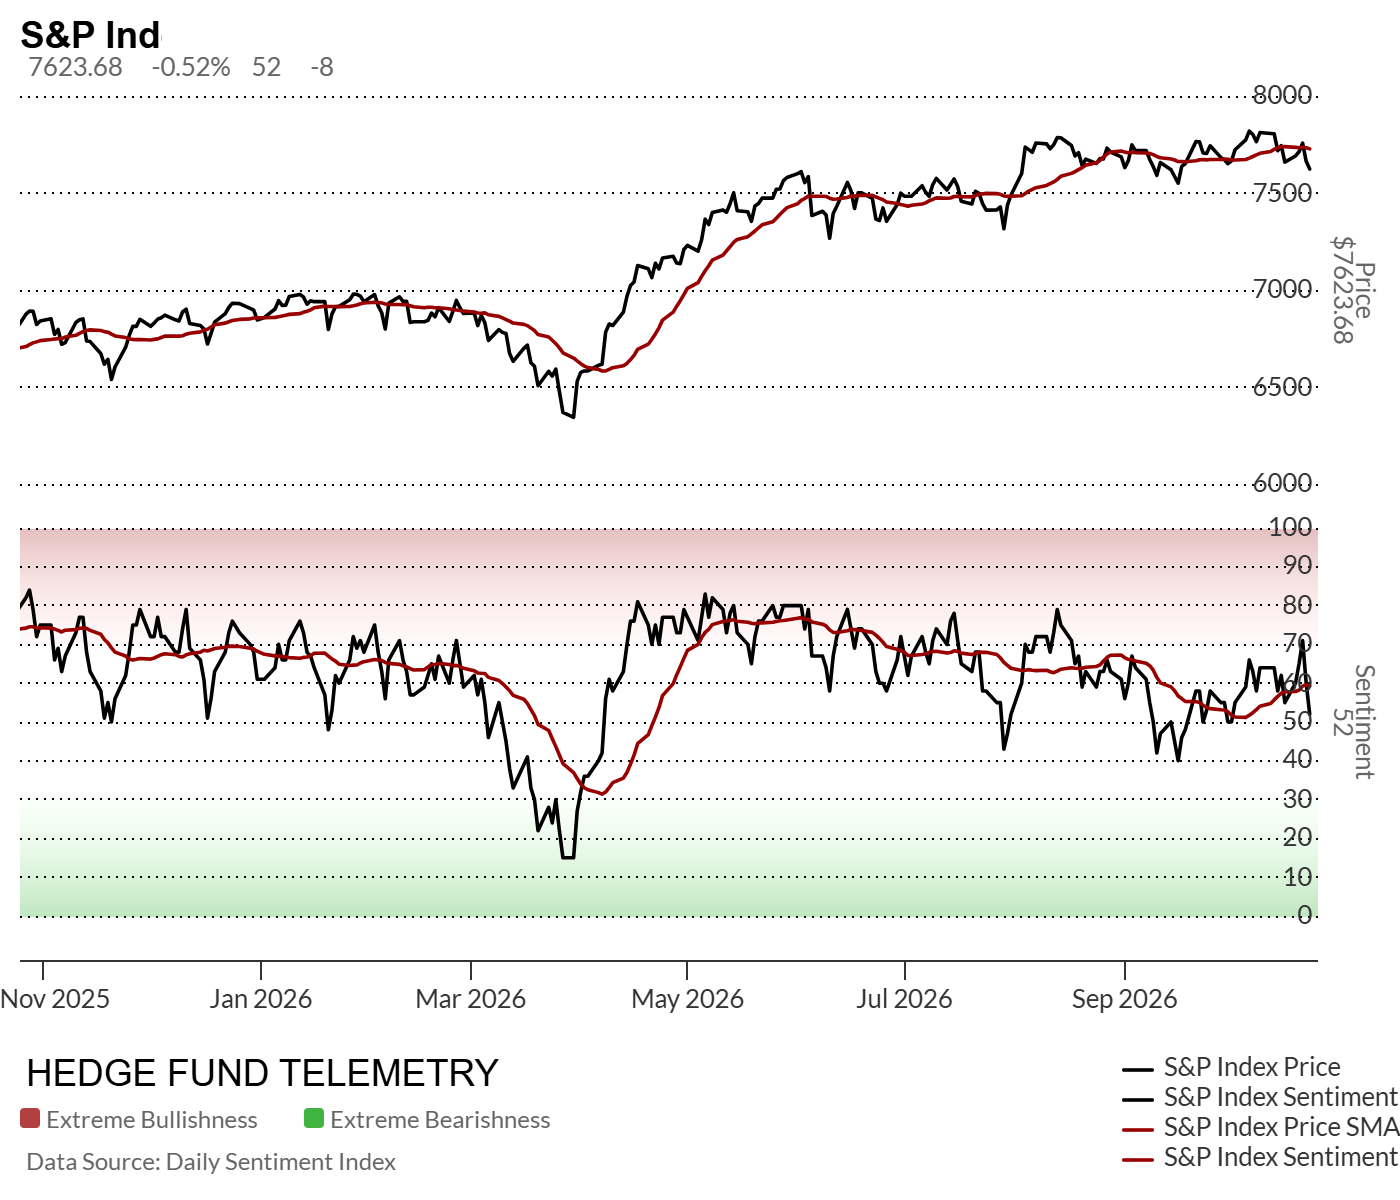
S&P 500: Bullish sentiment declined 8 points to 52%, following the prior session’s 11-point drop. That is a cumulative 19-point decline over two readings, leaving sentiment just above the critical 50% midpoint and 7.3 points below its 20-day average of 59.3%. The deterioration is significant, although not yet extreme.
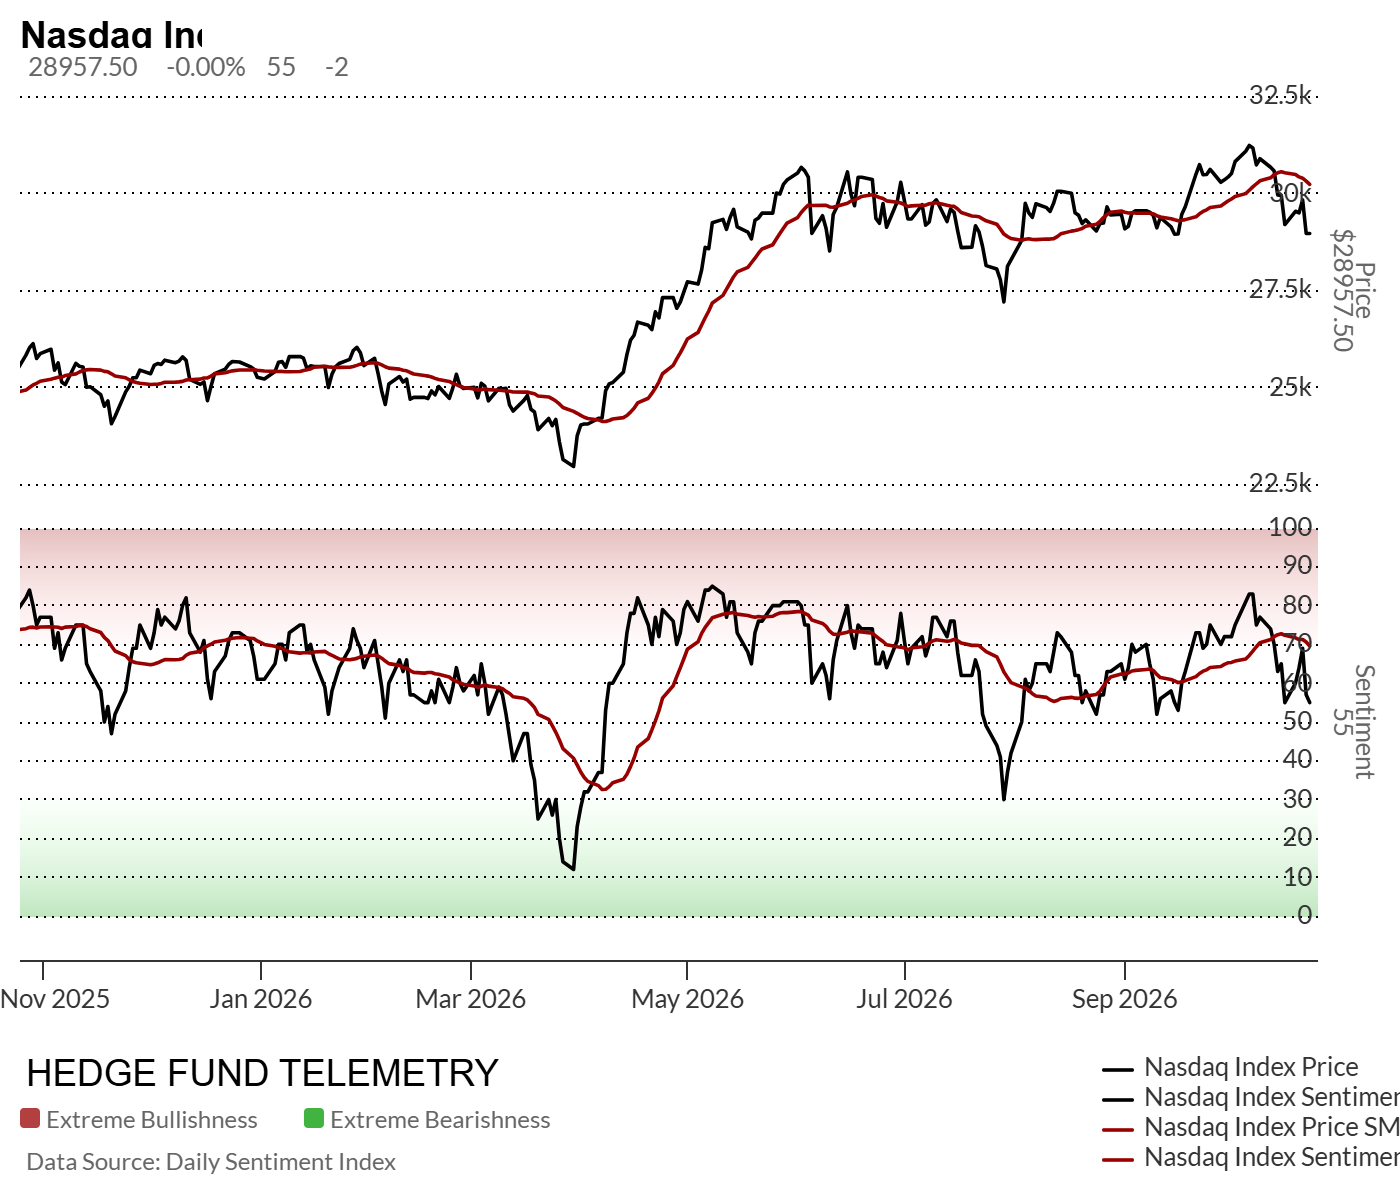
Nasdaq: Bullish sentiment slipped another 2 points to 55%, following the previous 12-point decline. The reading is 14.6 points below its 20-day average of 69.6%. Technology positioning has deteriorated materially, but sentiment remains above the 50% midpoint.
S&P and Nasdaq bullish sentiment charts are approaching the important 50% midpoint level support points.
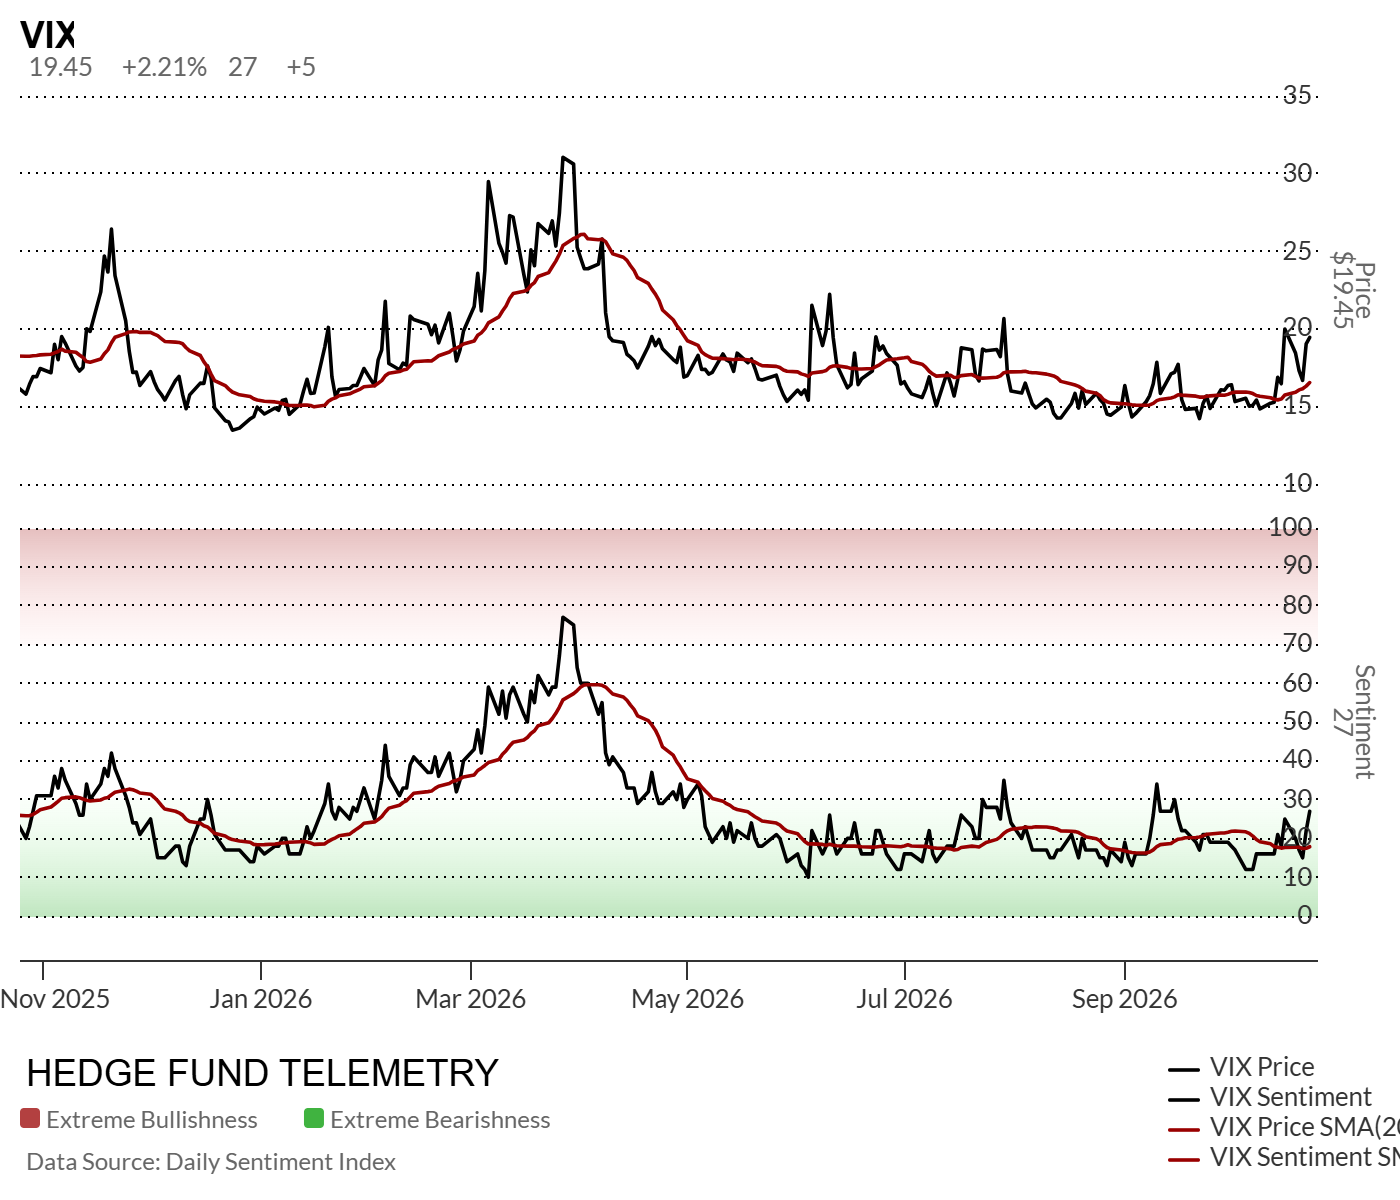
VIX: Bullish sentiment increased 5 points to 27%, following the prior 7-point increase. Volatility sentiment has recovered 12 points across two readings, while the VIX has advanced to 19.45. The move up from extremely depressed levels aligns with rising demand for downside protection.
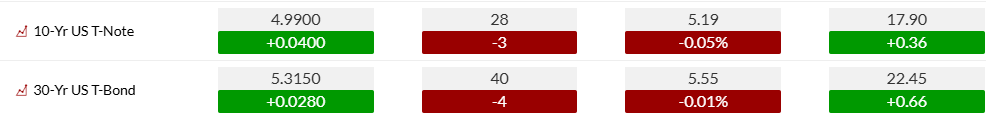
10-Year Treasury: Bullish sentiment declined 3 points to 28%, following the previous 8-point increase. The reading remains 10.1 points above its 20-day average of 17.9%, suggesting positioning has improved from deeply bearish levels despite the latest pullback.
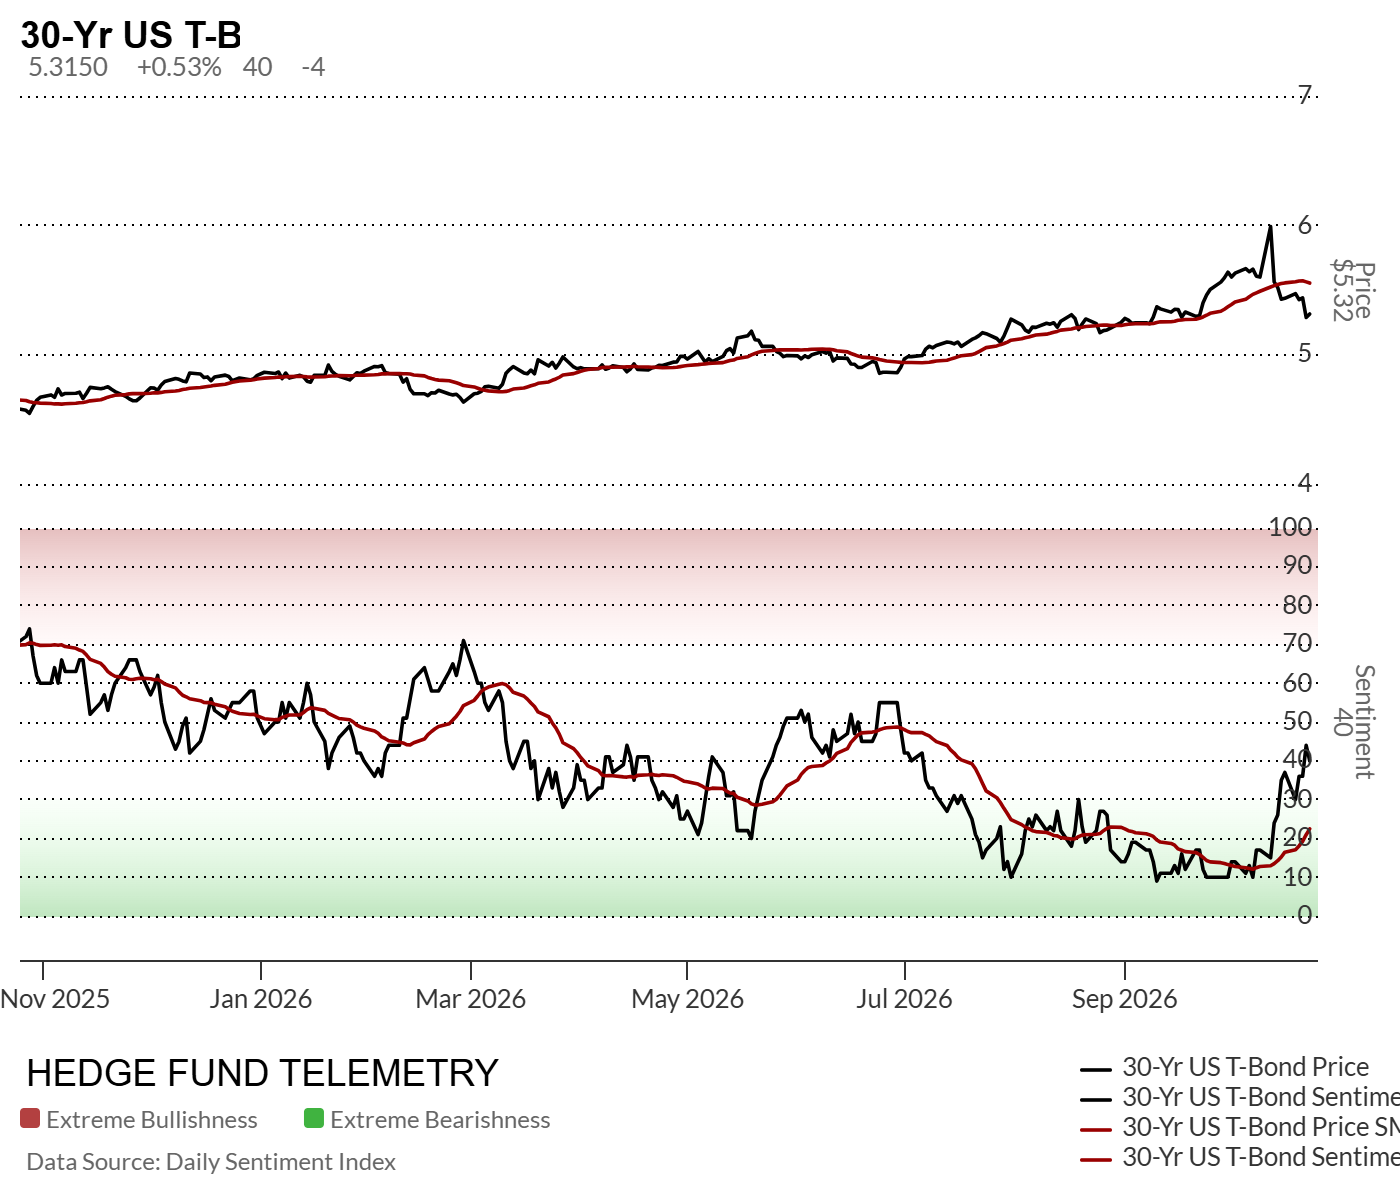
30-Year Treasury: Bullish sentiment declined 4 points to 40%, following the prior 8-point advance. Importantly, the reading remains 17.55 points above its 20-day average of 22.45%, reflecting a substantial shift toward duration.
Rates takeaway: Treasury sentiment has pulled back modestly following its recent improvement, but the underlying positioning shift remains intact. Both maturities remain below the 50% midpoint, suggesting duration demand is improving without becoming crowded. The reaction to GDP, PCE, and the FOMC will determine whether the recovery can continue.
A recent bond rally has shifted sentiment, with the 20-day moving average of bullish sentiment now rising. A clear break above the 50% midpoint would be another confirming metric.
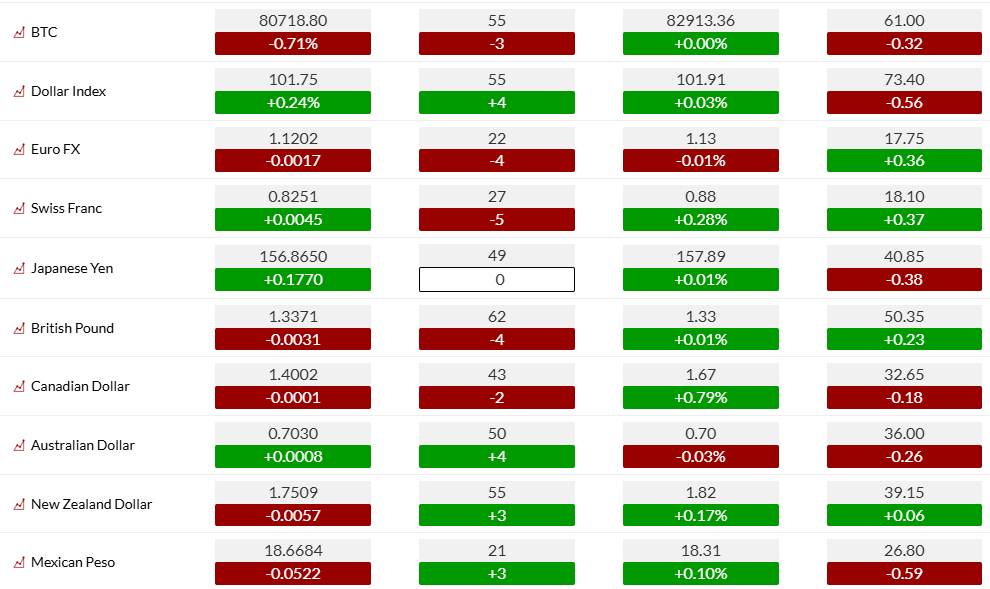
- Dollar Index: Bullish sentiment recovered 4 points to 55%, but remains 18.4 points below its 20-day average of 73.4%. The dollar is stabilizing after a substantial sentiment reversal, with positioning still materially below its recent norm.
- Euro: Bullish sentiment declined to 22%, approaching extreme bearish territory. European growth weakness and sovereign debt concerns remain potential headwinds.
- Yen: Bullish sentiment is unchanged at 49%, just below the 50% midpoint. The BOJ meeting and expectations for December tightening remain important catalysts.
- Australian Dollar: Sentiment improved to 50%, reaching the midpoint.
- Mexican Peso: Bullish sentiment increased to 21%, recovering slightly but remaining near extreme bearish territory.
FX takeaway: Dollar sentiment remains well below its 20-day average despite the latest rebound. The euro and peso are near bearish extremes, while the yen is approaching its midpoint. This is not a consistent risk-on currency configuration and suggests macro positioning remains unsettled.
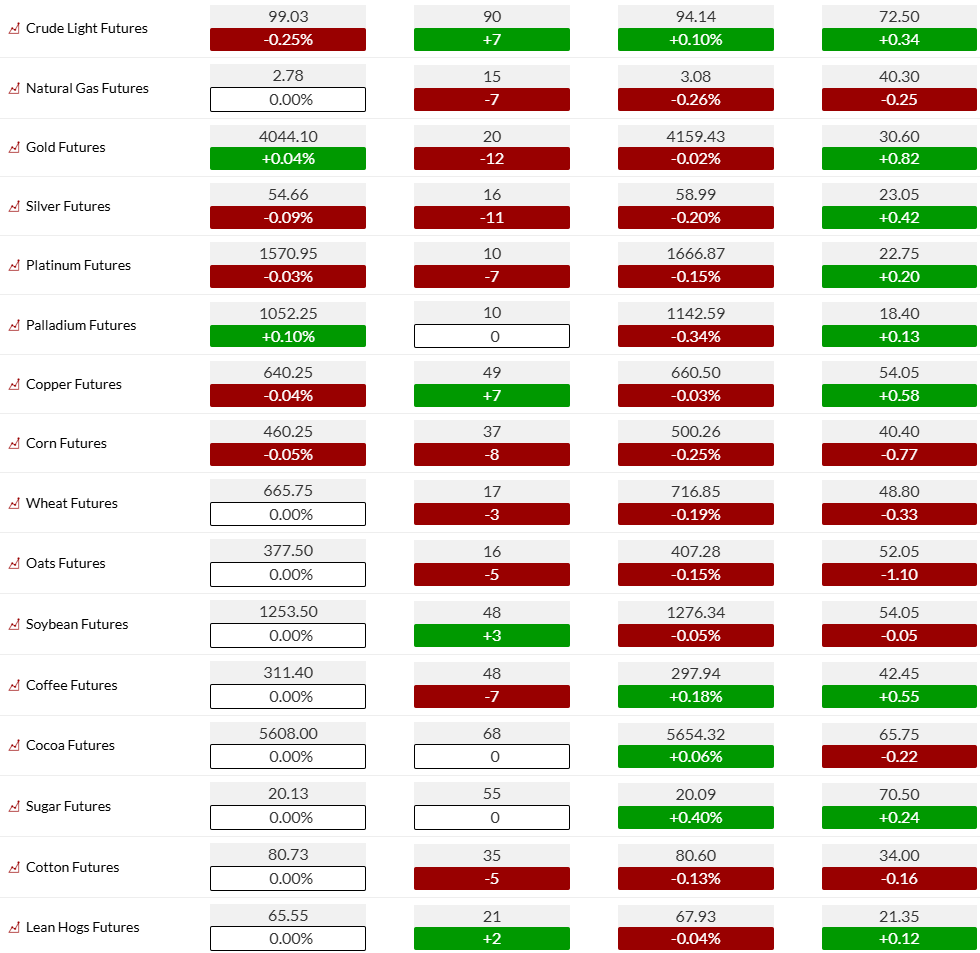
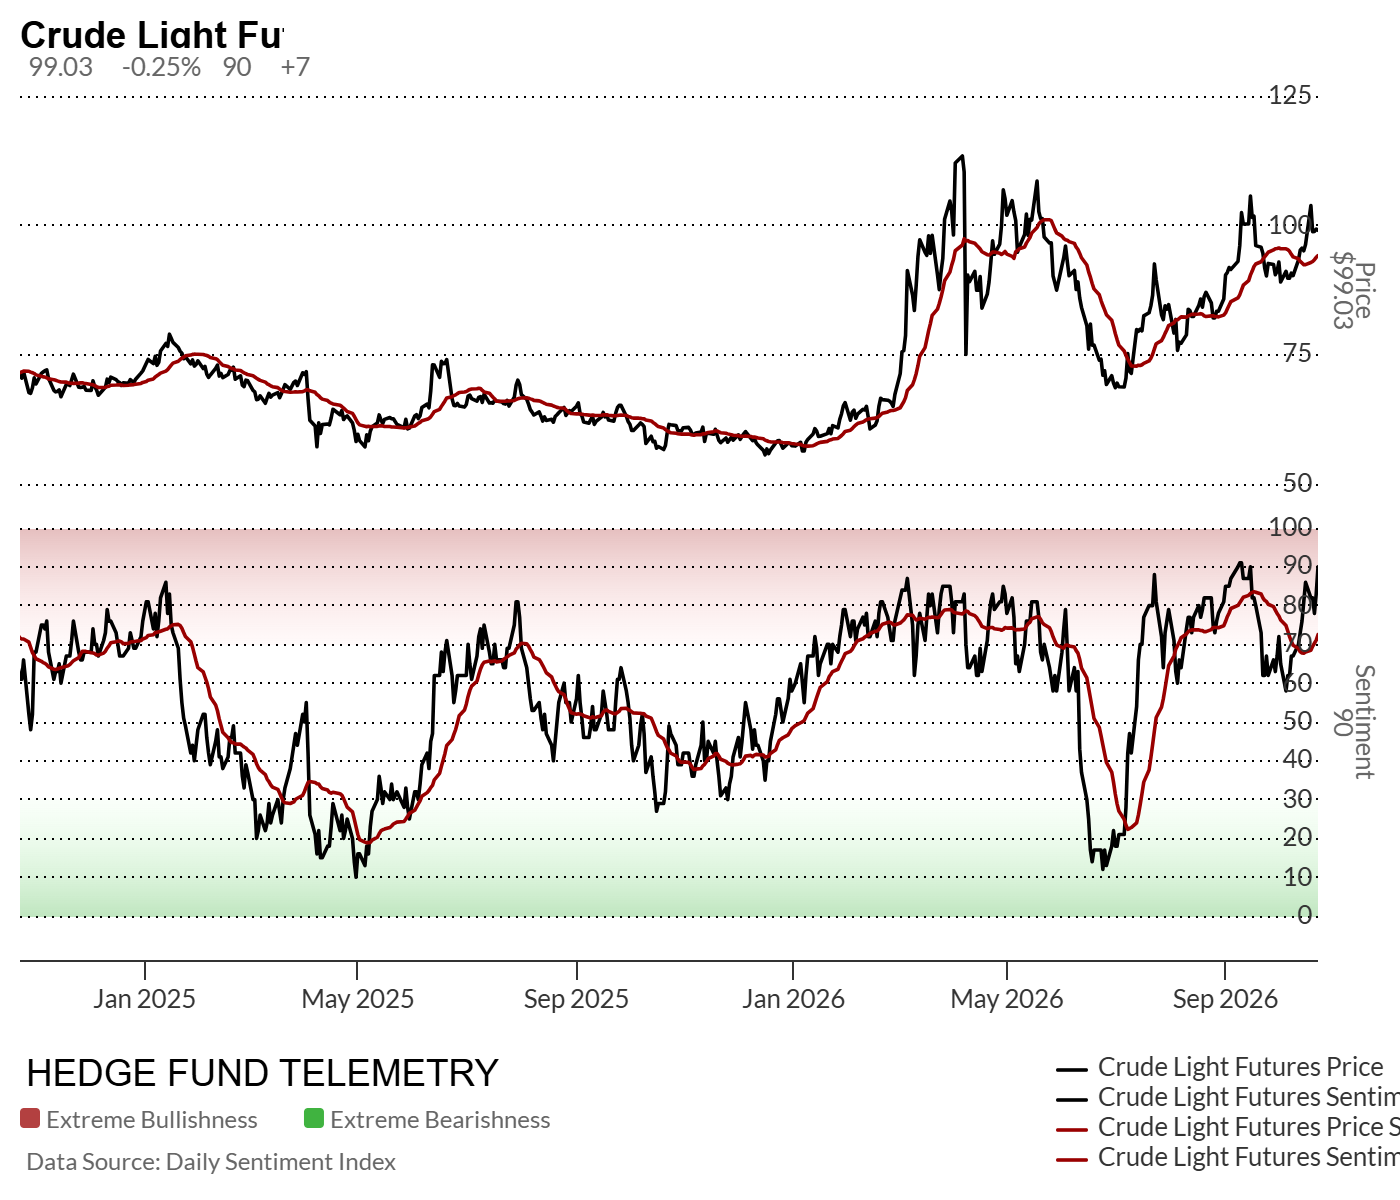
Crude Oil: Bullish sentiment surged another 7 points to 90%, extending its move into extreme bullish territory. The reading is now 17.5 points above its 20-day average of 72.5%. Geopolitical risk is supporting positioning, but at 90%, crude is increasingly vulnerable to a sharp reversal if tensions ease.
Natural Gas: Bullish sentiment declined 7 points to 15%, entering extreme bearish territory and standing 25.3 points below its 20-day average of 40.3%. This is a significant mean-reversion risk signal.
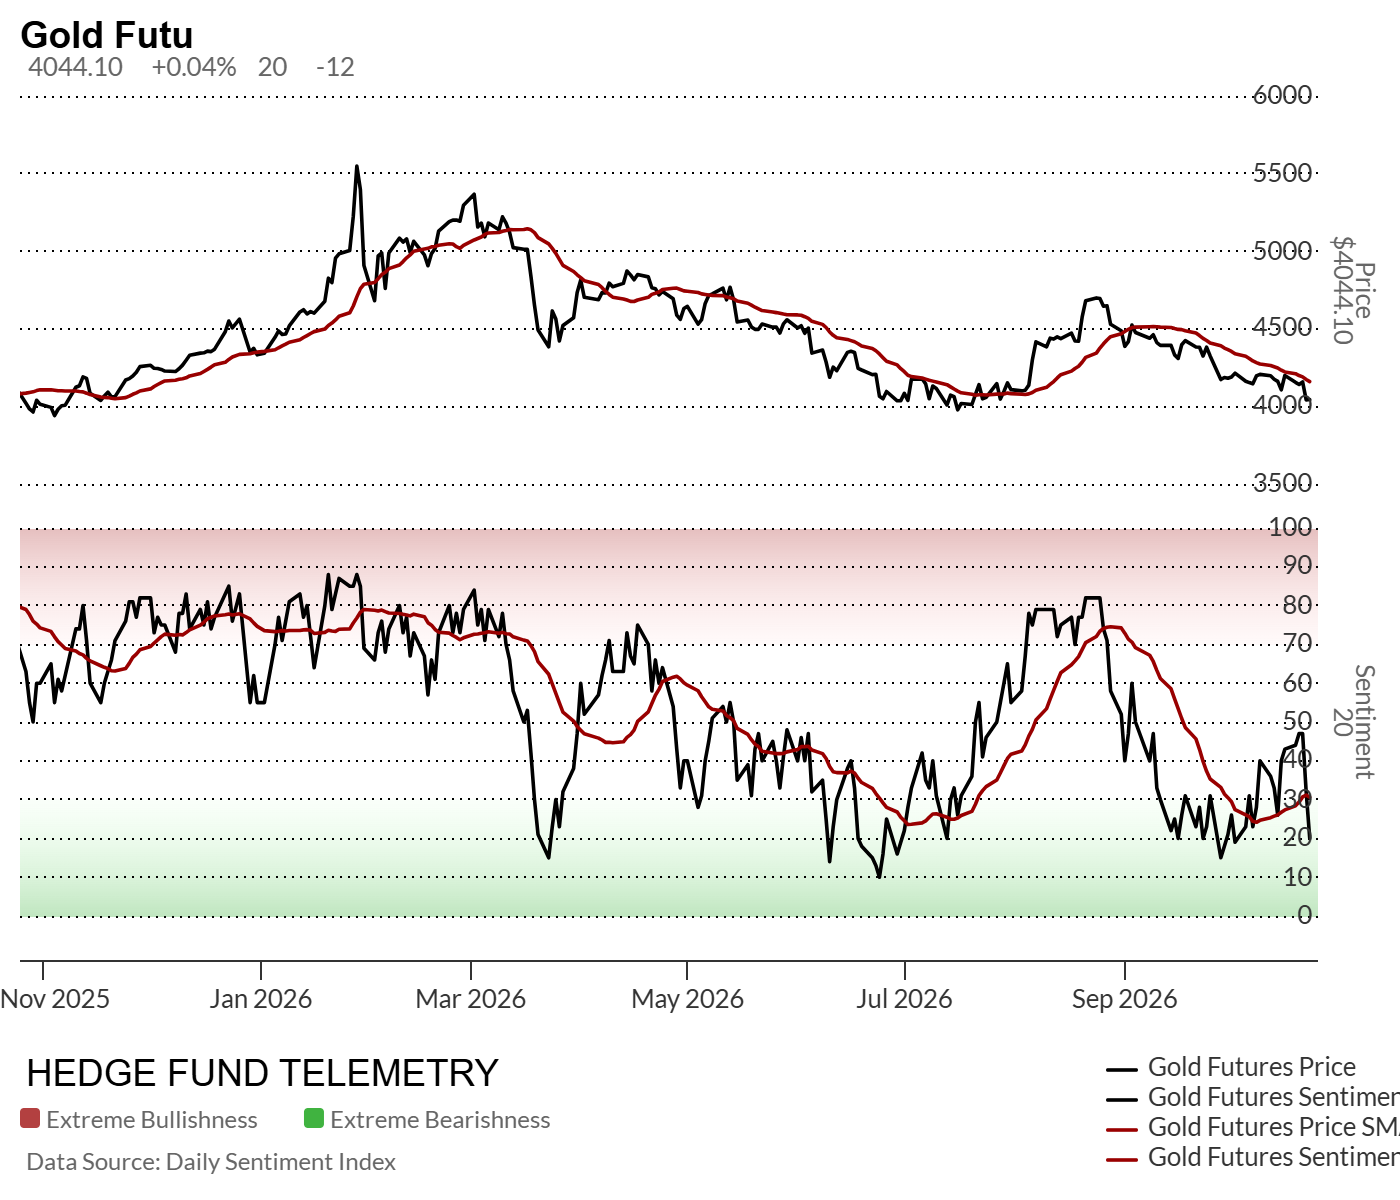
Gold: Bullish sentiment fell another 12 points to 20%, bringing the cumulative two-reading decline to 27 points. Gold sentiment is now at the boundary of extreme bearish territory, with the sharp liquidation occurring despite heightened geopolitical and equity risks.
Silver: Bullish sentiment declined another 11 points to 16%, entering extreme bearish territory. The cumulative decline of 25 points over two readings highlights significant liquidation pressure across precious metals. Platinum: Bullish sentiment fell 7 points to 10%, extending an already extreme bearish reading. Copper: Bullish sentiment recovered 7 points to 49%, approaching the 50% midpoint after the previous session’s sharp deterioration.
Agriculture: Corn sentiment declined 8 points to 37%, while wheat fell to 17%, entering extreme bearish territory. Oats sentiment also declined 5 points to 16%.
Commodity takeaway: The divergence between crude and other commodities has become extreme. Crude sentiment has reached 90%, while natural gas, silver, platinum, and wheat are in extreme bearish territory. This is a significant cross-asset positioning imbalance, with energy reflecting geopolitical supply risks while most other commodities reflect weaker demand expectations or liquidation pressure. A few commodities have pricing issues from the data feed.
Crude bullish sentiment at 90% has only occurred a few times in the last 5 years. A near-term pullback in crude is possible.
Gold bullish sentiment has dropped 27 handles in the last two sessions and is back in the extreme zone.
EARNINGS, CONFERENCES, ECONOMIC REPORTS
- Monday 26-Oct:
- Corporate:
- Earnings:
- Pre-open: 544397.IN, ABOS, ARLP, BFST, BMRC, BOH, DEA, MED, MMYT, VZ
- Post-close: AEYE, AGYS, AMKR, ARE, AVBH, BRO, BRX, CDNS, CINF, CLW, CTOS, DORM, FLXS, FSBC, FSUN, GBX, HIG, HTO, KFRC, NBN, NE, NUE, NWBI, PDM, PECO, PFG, PSA, PSMT, RMBS, SSD, TRTX, VLRS, WELL, WHR, ZDGE
- Analyst/Investor Events: FFAI; NVDA at ORCL AI World Conf
- Healthcare: BOLT to discuss acquisition of Prana Therapies (8:30ET); MRK Investor webcast at ESMO (14:30ET); CPIX webcast on ifetroban for CM associated with DMD (16:30ET)
- Brokerage Conference:
- European Society for Medical Oncology Congress
- IBM TechXchange
- PDUFA: MRK (ILUMYA)
- Earnings:
- Economic
- Europe: PPI y/y, IFO Business Climate
- Asia: Manufacturing Production NSA Y/Y, Preliminary GDP y/y
- Corporate:
- Tuesday 27-Oct:
- Corporate:
- Earnings:
- Pre-open: AB, ABG, ACU, AIT, AMT, ARCC, AWI, BA, CAC, CBC, CBU, CMS, CNC, CNP, CTS, CVLT, DQ, ECL, EEFT, ESQ, FCX, GLW, GLXY, HCA, HLT, HRI, HUBB, IBCP, INIO, IQV, ITRI, ITW, IVZ, JBLU, JCI, KO, LECO, MRP, NAUT, NWFL, PCAR, PNR, PROV, PYPL, RCL, RGEN, SFD, SHW, SMPL, SNDL, SOFI, SPGI, SXC, TNL, TRU, UPS, WSO, WVE, XYL
- Post-close: AAT, ACGL, APAM, BANC, BBAI, BBNX, BKR, BOOM, BRSP, BXP, CAKE, CHE, CR, CSGP, CTO, ENPH, EQT, ESS, EXE, EXLS, EXR, FCF, FE, FFBC, FFIV, HAFC, HIW, HOOD, ICLR, INTA, IVT, KIDS, LOGI, LPLA, LSTR, LU, LUNG, MANH, MIR, NBHC, NBR, NBTB, NOV, NTB, NXPI, OCFC, OI, ORN, PGC, PPG, RBBN, RCKY, RNR, RNST, ROG, RRC, RUSHA, SBCF, SEVN, SLDE, ST, STAG, STX, TER, TRMK, UCTT, UHS, UMBF, V, VTR, WERN, WM, WPC, ZWS
- Analyst/Investor Events: LBRX, ZBIO
- Brokerage Conference:
- European Society for Medical Oncology Congress
- IBM TechXchange
- Planet MicroCap Showcase
- MRO Europe Conference
- Earnings:
- Economic
- US: Durable Orders, FHFA House Price Index, New Home Sales, Consumer Confidence, Redbook Chain Store, ADP Weekly Employment, API Crude Inventories
- Europe: Trade Balance, Consumer Confidence, M3 Money Supply y/y
- Corporate:
- Wednesday 28-Oct:
- Corporate:
- Earnings:
- Pre-open: ADP, AEP, AER, AMRN, AON, APH, AVTR, AXGN, BIIB, BLCO, BLKB, BSX, CHEF, CHRW, CLH, CPF, CSTM, DAN, DBD, DINO, DMC, EAT, ETSY, EVR, EXTR, FELE, FLEX, FTV, GEHC, GEV, GNRC, GPI, GRMN, HAYW, HOPE, IEX, IP, JLL, JMKE, KEX, LFUS, LH, LII, MAS, MGPI, MTLS, NHTC, NI, ODFL, OGE, OPFI, OSW, OTIS, OTLY, PB, PRG, PSN, PSX, PUMP, RDWR, SCL, SHEN, SIFY, SITE, STNG, SW, TEL, TEX, UE, ULCC, VFC, VRT, WING
- Post-close: ADAM, AIN, ALGN, ALKT, ALRS, AM, AMRZ, AMSF, AR, AUR, AWK, AWRE, AXS, BELFB, BHC, BHE, BNL, BOOT, CBAN, CCS, CHDN, CLB, CLMB, CLPT, CMG, CMPR, CNMD, CNXN, COHU, CSL, CVNA, CYH, EBAY, EFOR, EG, EGO, EHC, EIG, EPAC, EPR, EQIX, F, FBRT, FCPT, FDX, FINW, FLS, FORM, FTNT, GBFH, GEN, GFL, GKOS, GOOGL, GRBK, HAPN, HDSN, HLI, HONA, HRTG, ILPT, INVH, JBSS, KGC, KLAC, KREF, LXU, MAA, MAX, MCHB, MDXG, MGM, MGRC, MRAM, MSFT, MTH, MVIS, MYRG, NEO, NEU, NEWT, NNBR, NOW, NWPX, NXT, OBK, OLED, ORLY, PBI, PFS, PI, PLXS, PPC, PRCH, PTEN, QTWO, RJF, RM, RSI, RYZ, SCI, SFM, SIMO, SPOK, STRL, TDOC, TENB, THG, TMUS, TYL, UFPI, UVSP, VICI, VKTX, VNDA, WEX, WHD
- Analyst/Investor Events: AAPL Pro & Tell Day; ORCL AI World; SBC; PH Annual General Meeting
- Brokerage Conference:
- IBM TechXchange
- Planet MicroCap Showcase
- New Orleans Investment Conference
- Red Cloud’s Fall Mining Showcase
- Earnings:
- Economic
- US: FOMC Meeting/Target Upper Bound; MBA Mortgage Purchase Applications, Wholesale Inventories (Preliminary), DOE Crude Inventories
- Canada: BoC Interest Rate/Overnight Rate Target
- Europe: Core Retail Sales m/m, PPI y/y
- Corporate:
- Thursday 29-Oct:
- Corporate:
- Earnings:
- Pre-open: AAMI, ABEV, AGCO, ALGM, ALNY, AMP, AOS, APG, ARES, ASPS, ATI, AVY, AXTA, BAND, BAX, BC, BCBP, BDC, BFLY, BG, BLDR, BMY, BWA, BWFG, BXMT, CARR, CAT, CFR, CNX, CRH, CROX, CSW, CTSH, CWT, DAR, DFIN, DHI, DRS, DTM, EME, ENTG, EPD, ESTA, FCN, FOR, FSS, FTAI, FTI, FTRE, FVRR, GATX, GTX, GVA, H, HGV, HII, HIPO, HOG, HSY, HWM, ICE, IDA, IDCC, INCY, INSM, KBR, KIM, LAUR, LGND, LHX, LIN, LKQ, LLY, LNG, LTH, MA, MBLY, MCS, MD, MO, MRK, MYE, NCLH, NEXT, NMRK, NSP, NVCR, OMCL, OSK, OWL, PATK, PBF, PGY, PHAT, PHIN, POR, PRLB, PWP, PWR, QSR, QUAD, RES, RJET, SAH, SAIA, SBSI, SILC, SIRI, SLGN, STGW, STRZ, TAL, THC, TNET, TPG, TRN, TROW, TRS, TT, TW, TWI, TXT, UPBD, VMC, WCC, WNC, WST, WTBA, WTW, XEL, XPO, XRX
- Post-close: ACCO, ACIC, AJG, ALHC, AMZN, ASBH, ASUR, ATEC, ATOM, ATR, AX, AXTI, BFAM, CDNA, CDP, CNO, COIN, COLM, COUR, CUBE, CUZ, CVLG, CVSA, DLR, DVA, DXC, DXCM, EIX, EMN, EXEL, EXPO, FBIZ, FDXF, FHI, FISI, FMC, FND, FORR, FSLR, GDDY, GDYN, GILD, GLPI, HG, HR, HTGC, ILMN, INBK, INGM, INTC, INVX, IR, IVR, KWR, LNT, MDLZ, MERC, MFIN, MHK, MIAX, MMSI, MPWR, MSTR, MTX, MTZ, MVBF, NPKI, OFS, OLN, OSIS, OSPN, PEB, PFSI, PINS, PMT, PRTS, PTCT, RBLX, RDDT, REAL, RIVN, RMD, RMNI, RSG, RYAN, SBUX, SKYW, SNDK, SNDR, SPSC, SPXC, STRT, SUPN, SYK, TBBK, TGS, TV, TWLO, VALE, VLTO, WKC, WTI, WY
- Analyst/Investor Meetings: BEP Extraordinary Shareholder Meeting
- Utility Regulatory: ETR Entergy Louisiana LA (U-37853) electric – hearings
- Brokerage Conference:
- IBM TechXchange
- PDUFA: XBRANE.SS (Xlucane); INO (INO-3107) BLA for adults with RRP 22:00
- Earnings:
- Economic
- US: Core PCE, Personal Spending/Income, GDP, Weekly Jobless Claims, EIA Natural Gas Inventories
- Europe: Preliminary GDP y/y, Retail Sales y/y, Unemployment Rate, BoE Mortgage Approvals, M4 MoneySupply m/m, Economic Sentiment Indicator, CPI y/y, Business Confidence, Consumer Confidence, PPI m/m
- Asia: Industrial Production m/m, Unemployment Rate, CPI Tokyo y/y, Industrial Production m/m (preliminary), Retail Sales y/y, Retail Sales m/m
- Corporate:
- Friday 30-Oct:
- Corporate:
- Earnings:
- Pre-open: ABBV, AN, BSAC, BTSG, CBOE, CHD, CL, CPRI, CVX, D, EXC, FET, FRT, GD, GTES, KRG, LEA, LYB, MHH, NVT, NWL, OABI, OIS, OMF, PIPR, RBC, REGN, SXT, TILE, TUSK, WT, XOM
- Analyst/Investor Events: N/A
- Utility Regulatory: EXC Delmarva Power & Light DE (D-25-1555) electric – intervenor testimony
- PDUFA: AGIO (PYRUKYND) sNDA for sickle cell disease (Sunday 1-Nov)
- Earnings:
- Economic
- US: Employment Cost Index, Chicago PMI
- Canada: GDP m/m
- Europe: PPI y/y, Consumer Goods Spending m/m, Preliminary GDP q/q, Retail Sales, Unemployment Rate, Preliminary GDP y/y, Nationwide House Price Index y/y, PPI m/m, Preliminary CPI y/y, KOF Leading Indicator, Retail Sales y/y, Unemployment rate, Preliminary (first) GDP y/y
- Asia: Non Manufacturing PMI y/y, official Manufacturing PMI y/y
- Corporate:
Thanks to Street Account, Vital Knowledge, and Bloomberg as valued sources.